Category: Close speed

  • In-House vs. Outsourced Bookkeeping and Accounting: Costs Compared and a Decision Framework for Growing Businesses

    In-House vs. Outsourced Bookkeeping and Accounting: Costs Compared and a Decision Framework for Growing Businesses

    The short answer: In-house vs. outsourced bookkeeping and accounting is a choice about how a company buys finance capacity. In-house means hiring whole people. Outsourced means buying fractions of three layers: recording, closing, and review. At 2026 national medians, a three-person in-house team costs about $429,886 a year fully loaded. The right answer depends on how much of each role the work actually fills.

    • A bookkeeper costs about $72,386 a year loaded, a staff accountant $119,543, and a financial manager $237,957.
    • Outsourced fees cover all three layers in one monthly price, including independent review.
    • In the worked example below, outsourcing saves $35,544 a year for a $9M distributor that needs 113 hours a month.
    • A single hire wins once the work fills about 90% of a full-time schedule, roughly 156 hours a month.
    • Five tests decide it: utilization, on-site presence, review coverage, continuity, and complexity.

    Last updated October 2026.

    Most comparisons of in-house and outsourced accounting set one salary against one monthly fee. That framing misses the structure of the work. A finance function has three layers, and each needs a different skill level.

    This guide prices all three layers from Bureau of Labor Statistics data, runs the math for one illustrative growing business, and closes with a five-test decision framework. A single-bookkeeper version of the cost question is covered in our guide to outsourced bookkeeping and how it works. Early-stage timing is covered separately in when startups should outsource bookkeeping.
    Watercolor of a wooden standing accounting desk with a slanted writing surface, from the Index of American Design
    William Spiecker, Bishop Hill: Accounting Desk, c. 1938, National Gallery of Art, via Wikimedia Commons, CC0.

    In-house vs. outsourced bookkeeping: what is the difference?

    The difference is who employs the people and how capacity is bought. In-house staff are employees paid for full schedules. An outsourced firm sells a defined scope for a monthly fee and staffs it from a shared team.

    The work itself splits into three layers. Recording covers coding transactions, entering bills, and reconciling bank and card accounts. Closing covers accruals, prepaid schedules, revenue recognition under ASC 606, and the monthly statements. Review means a senior person checks the balance sheet before anyone relies on it.

    Each layer maps to a different role. A bookkeeper handles recording. A staff accountant handles closing. A controller handles review. The distinction between the first two layers is covered in our explainer on bookkeeping vs. accounting.

    What does an in-house accounting team cost in 2026?

    About $429,886 a year for one person at each layer, at national median wages with benefits added. That is $35,824 a month before recruiting, software, or office costs.

    The figures below start from the BLS median annual wage for each occupation as of May 2025. Wages made up 70.0% of private-industry compensation in June 2026, according to the BLS Employer Costs for Employee Compensation release. Dividing each wage by 0.70 gives the fully loaded cost.

    LayerRole (BLS occupation)Median wage, May 2025Loaded cost per yearLoaded cost per monthLoaded cost per hour
    RecordingBookkeeper (bookkeeping, accounting, and auditing clerks)$50,670$72,386$6,032$34.80
    ClosingStaff accountant (accountants and auditors)$83,680$119,543$9,962$57.47
    ReviewController (financial managers)$166,570$237,957$19,830$114.40
    TotalThree-person team$300,920$429,886$35,824n/a

    Hourly figures assume 2,080 paid hours a year. Wage sources: BLS occupational data for bookkeeping clerks, accountants and auditors, and financial managers. Local markets run higher or lower than these national medians.

    What do salary comparisons leave out?

    They leave out utilization. A salary buys 173 hours a month whether the work needs 60 of them or all of them.

    Four other costs rarely show up in the comparison:

    • Review coverage. One in-house accountant cannot review their own work. Someone senior still has to check the balance sheet, and that time costs money.
    • Vacancy. When the only accountant resigns, the close stops. Recruiting, onboarding, and catch-up all land on the same months.
    • Management time. An employee needs a manager who can judge accounting work. In many growing companies, that manager is the CEO.
    • Tools and training. Seats for QuickBooks Online, NetSuite, or Bill.com, plus continuing education, sit outside the salary line.

    Outsourced fees carry their own costs. Someone inside the company still answers questions, approves payments, and supplies documents. A fair comparison counts that internal time on both sides.

    Worked example: in-house vs. outsourced for a $9M distributor

    Consider an illustrative wholesale distributor with $9M in annual revenue. Its books need about 113 hours of work a month: 70 hours of recording, 35 hours of closing, and 8 hours of review.

    Option A, lean in-house. The company hires one staff accountant to cover recording and closing. That is 105 hours of work in a 173-hour month, or about 61% utilization. The CEO spends 6 hours a month reviewing, valued at $200 an hour.

    • Staff accountant, loaded: $9,962 a month.
    • CEO review time: 6 × $200 = $1,200 a month.
    • Total: $9,962 + $1,200 = $11,162 a month.

    Option B, outsourced. An outside firm covers all three layers for an illustrative fee of $7,200 a month. The CEO spends 5 hours a month answering questions and approving the close.

    • Outsourced fee: $7,200 a month.
    • CEO time: 5 × $200 = $1,000 a month.
    • Total: $7,200 + $1,000 = $8,200 a month.

    The gap is $11,162 − $8,200 = $2,962 a month, or $35,544 a year. Option B also includes controller review, which Option A only approximates with the CEO’s time.

    Why does utilization decide the comparison?

    Because a salary is paid for every hour, used or not. The per-hour view shows the effect. The in-house hire costs $9,962 ÷ 105 = $94.88 per hour of work actually done. The outsourced fee works out to $7,200 ÷ 113 = $63.72 per hour. The hire matches that rate only when the work reaches $9,962 ÷ $63.72 = 156 hours a month. That is about 90% of a full-time schedule.

    The fee, the CEO rate, and the hour counts in this example are illustrative. The wage figures come from BLS data. Rerun the math with real quotes and real hours before deciding.

    How do you decide between in-house and outsourced accounting?

    Run five tests. Three or more in-house signals usually justify a hire. Fewer than three point to an outsourced or hybrid model.

    TestQuestion to askIn-house signalOutsourced signal
    1. UtilizationHow many hours does each layer need per month?140+ hours for one role, steady month to monthUnder about 120 hours, or uneven by season
    2. On-site presenceDoes the work need someone in the building?Inventory counts, cash handling, check runs, daily receivingFully digital records, bank feeds, cloud bill pay
    3. Review coverageWho checks the accountant’s work?A qualified controller or CFO already on staffNo one, or the CEO by default
    4. ContinuityWhat happens if the one finance person leaves?A second trained person can run the closeThe close stops until a replacement starts
    5. ComplexityHow many entities, currencies, and revenue streams?Daily judgment calls that need deep company contextStandard close with documented, repeatable steps

    Utilization carries the most weight. A role filled to 60% costs the same as one filled to 100%, and the idle 40% does not show up on any report.

    What does a hybrid finance model look like?

    A hybrid keeps the on-site, daily work in-house and outsources the close and review layers. It suits companies that pass test 2 but fail tests 3 and 4.

    A common shape is an in-house AP or operations coordinator who handles receiving, bill approvals, and vendor questions. The outsourced team reconciles accounts, posts accruals, closes the month, and reviews the balance sheet. The coordinator’s role often costs less than a staff accountant because it needs fewer accounting judgment calls.

    The handoff works best on a fixed calendar. Under the Continuous Close Method™, reconciliations run daily, so the month-end close becomes a review step rather than a catch-up project. Our Continuous Close Method guide explains the cadence. At Debit & Co., Aaron Ressel reviews close packets for hybrid clients before they ship.

    When does it make sense to bring accounting in-house?

    When the work fills full roles and the company can staff its own review. That usually means a workload above about 140 hours a month per layer, plus a controller or CFO who can supervise.

    Transitions usually happen in steps. A company might hire an in-house controller first, then keep outsourced support for recording and close capacity. It brings those layers in-house later, once volume justifies full roles. The reverse also happens: a company loses its only accountant and outsources the close to avoid a gap.

    Whatever the model, the company should own its ledger, its bank logins, and its records. That keeps any later switch, in either direction, clean. Our outsourced month-end close guide describes what a provider should hand back at each close.

    Frequently asked questions

    Is outsourcing bookkeeping and accounting a good idea for a growing business?

    It usually is when the workload fills less than about 90% of a full-time role, or when no one on staff can review the books. Outsourcing buys fractions of recording, closing, and review instead of whole salaries.

    How much does an in-house accounting team cost compared with outsourcing?

    At 2026 national medians, a bookkeeper, staff accountant, and financial manager cost about $429,886 a year fully loaded, or $35,824 a month. Outsourced fees vary with scope and volume, so compare quotes against the hours the work actually needs.

    Why do businesses outsource bookkeeping and accounting?

    The common reasons are partial utilization, the lack of an independent reviewer, and the risk of the close stopping when one employee leaves. Outsourcing also gives access to controller-level review without a full controller salary.

    Will bookkeeping become fully automated?

    Bank feeds and rules already automate much of transaction coding. Judgment work still needs people: accruals, revenue recognition, reconciliation exceptions, and balance sheet review.

    What is a hybrid accounting model?

    A hybrid keeps on-site, daily tasks such as receiving and bill approvals with an in-house coordinator. An outsourced team handles reconciliations, the month-end close, and review.

    Sources: U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, May 2025 (SOC 43-3031, 13-2011, 11-3031); U.S. Bureau of Labor Statistics, Employer Costs for Employee Compensation, June 2026. The distributor, the $7,200/mo fee, the $200/hr CEO rate, and the hour counts are illustrative.
  • Outsourced Bookkeeping, Explained: How It Works and When It Pays Off

    Outsourced Bookkeeping, Explained: How It Works and When It Pays Off

    The short answer: Outsourced bookkeeping means an outside team records transactions, reconciles every bank and card account, and closes the month inside your own QuickBooks Online or Xero file. It pays off when the work fills less than about two-thirds of a full-time role. A median bookkeeper costs about $72,386 a year once benefits are added, as of 2026.

    • You keep the ledger, the bank logins, and the records. The provider works through an accountant user.
    • The monthly cycle runs on a fixed calendar: weekly coding, month-end reconciliations, then statements by a set business day.
    • In the worked example below, the outsourced fee beats a full-time hire until the work passes roughly 116 hours a month.
    • A part-time hire looks cheaper on wages alone. The fee buys a second reviewer and coverage when someone leaves.

    Last updated October 2026.

    Outsourced bookkeeping is a service arrangement with a defined scope, a monthly calendar, and a fixed fee. Most of the confusion around it comes from not knowing what happens each week, who touches the ledger, or what the fee replaces.

    This guide explains the mechanics first. It then runs the cost math for one illustrative company that needs 28 hours of bookkeeping a month, using Bureau of Labor Statistics wage and benefit data. Timing questions, such as whether to start at first revenue or first payroll, are covered in our separate guide on when startups should outsource bookkeeping.

    Open nineteenth-century handwritten account book ledger belonging to painter John Carlin, with ink signatures and the word Philadelphia on the right-hand page
    John Carlin’s account book ledger, 1835–56, The Metropolitan Museum of Art, via Wikimedia Commons, CC0.

    What is outsourced bookkeeping?

    Outsourced bookkeeping is the recording, categorizing, and reconciling of a company’s transactions by an outside firm instead of an employee. The books stay in the company’s own accounting system.

    Scope is the part buyers most often misread. Bookkeeping produces accurate, reconciled records and monthly financial statements. Tax returns, audit work, and forecasting sit outside it, although many firms sell them as separate services.

    Usually in scopeUsually a separate service
    Coding bank and card transactions to the chart of accountsFederal and state income tax returns
    Monthly reconciliation of every bank, card, and loan accountPayroll processing and payroll tax filings
    Bill entry and vendor records in Bill.com or the ledgerCash flow forecasting and budgeting
    Customer invoices and accounts receivable trackingRevenue recognition under ASC 606
    Monthly P&L, balance sheet, and statement of cash flowsBoard reporting and investor updates

    Read every proposal against this table. Two quotes that differ by $400 a month often differ in scope, not in price.

    How does outsourced bookkeeping work month to month?

    It runs on a fixed monthly calendar. Transactions are coded during the month, accounts are reconciled after it ends, and statements arrive by an agreed business day.

    A typical cycle has four stages.

    • Weekly, days 1–30: bank feeds pull transactions into QuickBooks Online, and the team codes them. Open questions go to one contact in a single batched list.
    • Business days 1–3: the team imports final bank and card statements, then reconciles each account to the penny.
    • Business days 4–7: accruals, prepaid expenses, and payroll entries are posted, and a second person reviews the balance sheet.
    • Business days 8–10: the close packet is delivered with the three statements, reconciliation reports, and AR and AP aging.

    The review step separates a bookkeeping service from a single contractor. One person codes; another checks the balance sheet before anything leaves. Our outsourced month-end close guide walks through that review layer in more detail.

    Who owns the books and the records?

    The company does. The provider works inside the company’s own ledger through an accountant or user login, and access ends when the engagement ends.

    That ownership matters for record retention. The IRS guidance is direct: “Keep employment tax records for at least 4 years after the date that the tax becomes due or is paid, whichever is later.” General income tax records follow a 3-year rule in the standard case, per its page on how long to keep records. A provider that keeps the books in its own system can leave the company without those records after a switch.

    Ask three questions before signing. Whose subscription holds the ledger? Who holds the bank credentials? How does the firm control access to client data? Our checklist on outsourcing partner data security and SOC 2 covers the third question.

    What does an in-house bookkeeper actually cost?

    About $72,386 a year at the national median, once employer benefits are added. Salary alone understates the cost by roughly 30%.

    The Bureau of Labor Statistics reports a median annual wage of $50,670 for bookkeeping, accounting, and auditing clerks as of May 2025, or $24.36 an hour. Its Employer Costs for Employee Compensation series shows that wages made up 70.0% of private-industry compensation in June 2026. Benefits supplied the other 30.0%, or $14.07 of every $46.89 per hour worked.

    Run the arithmetic. A $50,670 salary divided by 0.70 gives a loaded cost of $72,386 a year, or $6,032 a month. The same adjustment turns $24.36 an hour into $34.80 an hour. That figure still excludes recruiting, software seats, training, and the weeks a role sits empty after a resignation.

    When does outsourced bookkeeping pay off?

    It pays off when the workload is too small for a full-time hire and too important for the founder. In the example below, that range runs from a few hours a month up to about 116.

    Take a services company with $3.8M in revenue, three bank accounts, two corporate cards, and about 350 transactions a month. Its books need 28 hours of work each month. One provider quotes $1,450/mo for bookkeeping plus a reviewed close, which is an illustrative figure for this example.

    Option for 28 hours/monthMonthly costAnnual costSecond reviewerCoverage if the person leaves
    Founder does it (time valued at $150/hr)$4,200$50,400NoNone
    Full-time in-house bookkeeper$6,032$72,386NoRehire, 1–3 months
    Part-time in-house, 28 hours at $34.80$974$11,693NoRehire, 1–3 months
    Outsourced bookkeeping$1,450$17,400YesTeam continues

    The math has two lessons. First, the full-time hire costs $72,386 − $17,400 = $54,986 more a year, because 28 hours fill only 16% of a 173-hour work month. Second, the part-time hire is cheaper by $17,400 − $11,693 = $5,707 a year. That gap pays for a reviewer, a close calendar, and continuity, which a single part-time employee cannot supply.

    Where is the break-even between outsourcing and hiring?

    In this example, at about 116 hours of bookkeeping a month. Below that, the outsourced fee costs less than a full-time employee.

    The fee works out to $1,450 ÷ 28 = $51.79 per hour of work. A full-time hire becomes cheaper once monthly hours pass $6,032 ÷ $51.79 = 116.5, or about two-thirds of a full schedule. Our comparison of outsourced accounting cost vs. in-house extends this math to controllers.

    When is outsourced bookkeeping the wrong choice?

    It is the wrong choice when the work needs a person on site, or when volume fills most of a full-time role. Both situations favor an employee.

    Physical tasks are the clearest case. Counting inventory, handling cash deposits, and collecting paper receipts from a warehouse floor cannot happen from another office. Volume is the second case: past roughly 116 hours a month in the example, the employee wins on direct cost.

    Even then, many companies keep an outside layer. An in-house bookkeeper handles daily entries, while an outsourced controller reviews the close each month. The handoffs between those roles are mapped in bookkeeper vs. controller vs. CFO.

    How do you switch to an outsourced bookkeeper?

    Start with a diagnostic of the current books, then a defined handover month. The sequence below spans about two months from signed scope to the first delivered close.

    • Week 1: grant accountant-level access to QuickBooks Online, Bill.com, the payroll system, and read-only bank feeds.
    • Weeks 2–3: the provider reviews the chart of accounts and open reconciliations, then lists any months that need catch-up.
    • Weeks 3–4: agree the close calendar, the contact for questions, and the packet contents.
    • Month 2: the first full close is delivered and reviewed together, line by line.

    Books more than a few months behind need catch-up work first, priced separately. Our outsourced startup bookkeeping page outlines how that onboarding is structured.

    How does Debit & Co. run outsourced bookkeeping?

    Under the Continuous Close Method™, accounts are reconciled weekly during the month, so close week verifies balances instead of rebuilding them. Each entry keeps the source document that supports it.

    For clients on Puzzle, the ledger arrives already categorized; the team turns that data into a reviewed close. Aaron Ressel reviews the balance sheet in each close packet before it ships to the client.

    Frequently asked questions

    What is outsourced bookkeeping?

    Outsourced bookkeeping is the recording, categorizing, and reconciling of a company’s transactions by an outside firm instead of an employee. The work happens inside the company’s own QuickBooks Online or Xero file, and the firm delivers monthly financial statements on a fixed calendar.

    How does outsourced bookkeeping work?

    Transactions are coded weekly through bank feeds, every bank and card account is reconciled after month end, a second person reviews the balance sheet, and a close packet with the P&L, balance sheet, and cash flow statement arrives by an agreed business day, typically day 8–10.

    How much does an in-house bookkeeper cost compared with outsourcing?

    The BLS median wage for bookkeeping clerks was $50,670 in May 2025. With benefits at 30.0% of compensation, the loaded cost is about $72,386 a year. In the worked example, a $1,450/mo outsourced fee costs $17,400 a year for 28 hours of monthly work.

    When does outsourced bookkeeping pay off?

    It pays off when the workload is too small for a full-time hire. In the example, the outsourced fee works out to $51.79 per hour of work, so a full-time bookkeeper only becomes cheaper above about 116 hours a month, roughly two-thirds of a full schedule.

    Who owns the books when bookkeeping is outsourced?

    The company should. The ledger subscription, bank credentials, and records stay with the company, and the provider works through an accountant login. The IRS says to keep employment tax records for at least 4 years, so the company must retain access after any switch.

    Sources: U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, May 2025 (SOC 43-3031); BLS Employer Costs for Employee Compensation, June 2026; IRS, How long should I keep records. The company example and the $1,450/mo fee are illustrative.

  • What a Fractional CFO Adds to Your Monthly Close: Reviews, Flux Analysis, and Board-Ready Reporting

    What a Fractional CFO Adds to Your Monthly Close: Reviews, Flux Analysis, and Board-Ready Reporting

    The short answer: The CFO role in the monthly close is review, explanation, and reporting. The bookkeeper and controller produce the books; the fractional CFO checks the judgment entries, explains every material movement, and turns the result into a board-ready packet. In the worked example below, that review moved reported gross margin by 1.7 points before anyone outside finance saw it.

    • A fractional CFO oversees the close; the controller runs it.
    • The review targets judgment accounts: deferred revenue, accruals, reserves, and capitalized costs.
    • Flux analysis caught a $7,200 duplicate vendor invoice hiding inside a 31.3% hosting jump.
    • A funded company should close by business day 5–7 and ship the packet by day 8–10.

    Last updated October 2026.

    Most companies hire a fractional CFO for forecasting and fundraising. The monthly close is where that work either holds up or falls apart. A forecast built on a misstated September carries the error into every month that follows.

    This guide covers what the CFO does during each close, how the role differs from the controller’s, how flux analysis works in practice, and what reporting should come out the other end. All figures come from one illustrative B2B software company closing September 2026.

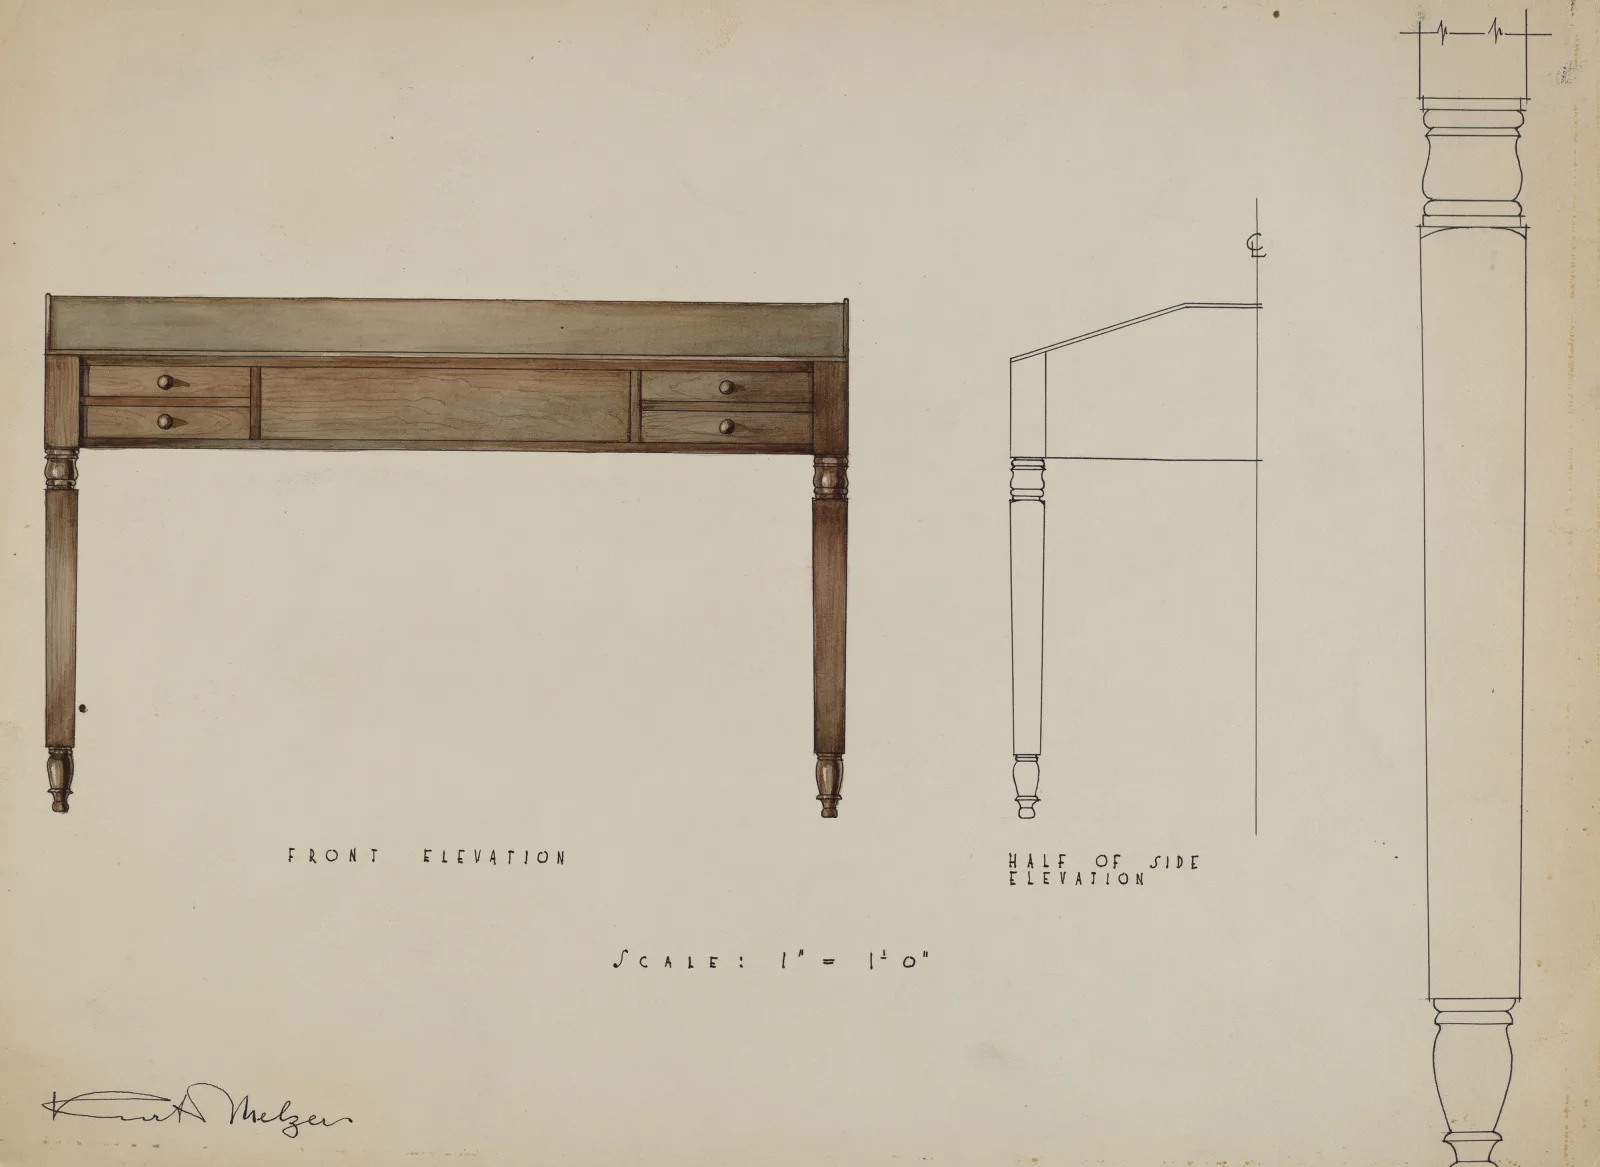
    Watercolor elevation drawing of a four-drawer accounting desk with turned legs, from the Index of American Design, 1936
    Kurt Melzer, Accounting Desk, 1936. National Gallery of Art via Wikimedia Commons, CC0.

    Does a fractional CFO do the monthly close, or oversee it?

    A fractional CFO oversees the close. The bookkeeper posts transactions and the controller reconciles and drafts the statements; the CFO reviews, questions, and signs off.

    The split matters for cost. Reconciling a bank account in QuickBooks Online is controller work, and paying CFO rates for it wastes the budget. The CFO’s hours belong on the entries that require judgment and on the explanation that a board will read.

    In the example company, the CFO’s close work takes 9 hours a month. Judgment-entry review takes 3.5 hours, flux review 2.5 hours, packet commentary 2 hours, and the sign-off call 1 hour: 3.5 + 2.5 + 2 + 1 = 9. Everything else in the close belongs to the accounting team.

    What is the CFO role in the monthly close vs. the controller’s?

    The controller owns accuracy and timing. The CFO owns interpretation and sign-off. Both read the same trial balance, but they ask different questions of it.

    The controller asks whether each account is complete and reconciled. The CFO asks whether the numbers describe the business that management believes it is running. The table shows how the work divides across a five-day close.

    Business dayBookkeeperControllerFractional CFO
    Days 1–2Clears bank and card feeds; posts bills from Bill.com and invoicesReconciles cash, receivables, and payablesNone
    Day 3Answers coding questionsBooks accruals, deferred revenue, and prepaid schedulesReviews judgment entries
    Day 4Fixes miscoded transactionsDrafts statements and the flux listReviews flux and writes explanations
    Day 5NonePosts corrections and locks the periodSigns off on the final numbers
    Days 6–8NoneSupports schedules for the packetWrites commentary and ships the board packet

    A fuller comparison of the three seats sits in bookkeeper vs. controller vs. CFO. Companies in their first month with a CFO follow a different sequence, covered in what a fractional CFO does in month one.

    Which entries does a CFO review before the books lock?

    The CFO reviews the entries where two reasonable accountants could book different numbers. Those are revenue recognition, accruals, reserves, and costs that might be capitalized.

    • Deferred revenue. Annual contracts billed upfront are earned over the service period under ASC 606.
    • Accruals. Services received in September but invoiced in October still belong in September.
    • Reserves. The allowance for doubtful accounts should match the aging of receivables.
    • Capitalized costs. Software development and equity awards under ASC 718 need a documented policy.

    One review caught this error. A customer signed a $38,400 annual subscription on September 1 and paid upfront. The bookkeeper recorded the full amount as September revenue. Earned ratably, the contract yields $38,400 ÷ 12 = $3,200 a month, so $35,200 belonged in deferred revenue.

    Unreviewed, September revenue would have shown $447,800 instead of $412,600. That is an overstatement of $35,200, or 8.5% of true revenue. A board shown $447,800 would have read a growth spike that did not exist.

    What is flux analysis, and what does it catch?

    Flux analysis compares each line of the financial statements with the prior period and explains every material change. It is the fastest way to find errors that reconciliations miss.

    A reconciliation proves that a balance matches a bank or a subledger. It cannot prove that an expense belongs where it was coded. Flux analysis catches that class of error because a misposted invoice changes the trend line.

    Line (2026)AugustSeptember, as draftedChangeSeptember, corrected
    Revenue$398,100$412,600+$14,500 (+3.6%)$412,600
    Hosting$24,300$31,900+$7,600 (+31.3%)$24,700
    Support payroll$58,200$58,900+$700 (+1.2%)$58,900
    Gross profit$315,600$321,800+$6,200 (+2.0%)$329,000
    Gross margin79.3%78.0%−1.3 points79.7%

    How does the CFO explain a flagged flux line?

    The CFO traces the movement to a source document and states the cause in one sentence with a dollar amount. Hosting rose 31.3% while revenue rose 3.6%. Usage does not grow nine times faster than revenue in one month, so the CFO asked for the vendor detail. The hosting provider had billed one August invoice a second time: $7,200 was a duplicate, and $400 was real usage growth.

    Corrected, hosting is $24,300 + $400 = $24,700. Gross profit becomes $412,600 − $24,700 − $58,900 = $329,000, a margin of 79.7%. As drafted, margin fell 1.3 points. Corrected, it rose 0.4 points. That gap of 1.7 points is the difference between a margin warning and a margin improvement.

    Threshold setting and baselines are covered in variance analysis at month-end close. The CFO’s contribution is the explanation: a sentence on each flagged line that names the cause and the dollar effect.

    How fast should a monthly close be for a funded company?

    A funded company should close by business day 5–7. That timing lets the CFO ship a reviewed board packet by business day 8–10.

    The calendar shows why. September 2026 ends on a Wednesday. A 5-day close finishes on October 7; a 15-day close finishes on October 21, two weeks later. On a 15-day close, the board reads September during the last week of October, when most of the next month has already been spent.

    Speed without review is no improvement. A close that locks on day 5 with an unreviewed $35,200 revenue error is fast and wrong. The sequence that delivers both is set out in the five-day close calendar.

    What reporting should come out of the close each month?

    Every close should produce a board-ready packet with five parts. Each part ties back to the locked trial balance, so a director can trace any figure to its source.

    • Income statement with the flux commentary beside each flagged line.
    • Balance sheet with deferred revenue and receivables aging.
    • Cash and runway page with net burn as a trailing three-month average.
    • Budget-vs-actual table by department, in dollars and percent.
    • KPI page with gross margin, net revenue retention, and days to close.

    The cash page format is detailed in how to present burn and runway to your board. The commentary is what separates a board packet from an export. Directors should read why gross margin moved, not only that it moved.

    What does CFO sign-off on the close protect?

    Sign-off puts a named senior reviewer behind the numbers. Investors, lenders, and acquirers rely on that review when they act on monthly financials.

    Public companies make the requirement explicit. Section 302 of the Sarbanes-Oxley Act, codified at 15 U.S.C. § 7241, requires the principal financial officer to certify each quarterly and annual report. The certification states that the officer has reviewed the report and that the statements fairly present the company’s financial condition in all material respects.

    Private companies carry no such legal duty. The discipline still transfers. A company that has had a CFO sign off on 24 consecutive closes enters diligence with a documented review trail, which shortens the questions a buyer or auditor asks.

    How does the Continuous Close Method™ fit the CFO review?

    It spreads reconciliation across the month, so the CFO reviews finished accounts instead of waiting on unfinished ones. Review time goes to judgment calls rather than chasing missing data.

    Under the Continuous Close Method™, Debit & Co. reconciles bank and card accounts weekly, updates deferred revenue as contracts are signed, and logs vendor invoices against prior months as they arrive. Kevin Cahill signs off on the flux commentary in every close packet before it ships. The outsourced CFO services engagement includes this review in each monthly close.

    Frequently asked questions

    Does a fractional CFO do the monthly close, or oversee it?

    A fractional CFO oversees it. The bookkeeper posts transactions and the controller reconciles and drafts the statements. The CFO reviews judgment entries, explains material movements, and signs off. In the worked example, that oversight takes 9 hours a month.

    What is the CFO’s role in the close vs. the controller’s?

    The controller owns accuracy and timing: reconciliations, accruals, and draft statements. The CFO owns interpretation and sign-off: reviewing judgment entries, explaining flux, and writing the board commentary. The controller asks whether accounts are complete; the CFO asks whether the numbers describe the business.

    What is flux analysis and why does it matter?

    Flux analysis compares each financial statement line with the prior period and explains every material change. In the example, hosting rose 31.3% against 3.6% revenue growth, which exposed a $7,200 duplicate invoice and moved gross margin from 78.0% to 79.7%.

    How fast should a monthly close be for a funded company?

    A funded company should close by business day 5–7 and ship a reviewed board packet by business day 8–10. For September 2026, a 5-day close finishes on October 7, while a 15-day close finishes on October 21.

    What reporting should come out of the close each month?

    Five parts: an income statement with flux commentary, a balance sheet with deferred revenue and receivables aging, a cash and runway page, a budget-vs-actual table by department, and a KPI page with gross margin, net revenue retention, and days to close.

    Sources: 15 U.S.C. § 7241 (Sarbanes-Oxley Act § 302), via the U.S. Government Publishing Office. Worked example is illustrative.

  • The Continuous Close Method: How to Reconcile Daily and Deliver Books in 5-7 Days

    The Continuous Close Method: How to Reconcile Daily and Deliver Books in 5-7 Days

    The short answer: A continuous close moves reconciliation and coding into the month, so only 18 of roughly 90 close hours remain after month-end in the worked example below. That shift takes a single-accountant close from about 15 business days to 5.

    • Transactions are coded daily, bank and card accounts reconcile weekly, and a controller reviews exceptions every week.
    • Total effort barely changes: 88 hours in a batch close versus 90 hours spread across the month.
    • Month-end still exists. It shrinks to cutoff, accrual true-ups, review, and the packet.
    • QuickBooks Online, Xero, or NetSuite can all carry the method; cadence and ownership matter more than the ledger.

    Last updated October 2026.

    A continuous close is the practice of doing close work as transactions happen instead of after the month ends. Coding happens daily, reconciliations weekly, and review in small weekly batches. By the last business day, most of the ledger is already tied out.

    This guide defines the method, explains why a batch close runs past two weeks, and maps each task to a cadence. It then works through the hours for one illustrative company. The figures describe a hypothetical $22M B2B services firm as of October 2026.

    Engraved perpetual calendar disc listing the seven days of the week, from The Metropolitan Museum of Art
    Perpetual calendar, The Metropolitan Museum of Art, via Wikimedia Commons, CC0.

    What is a continuous close?

    A continuous close spreads the month-end workload across the month on fixed cadences. The goal is a ledger that is substantially reconciled before the period ends, so the formal close becomes a short confirmation step.

    Debit & Co. runs this approach as the Continuous Close Method™. Its three rhythms are simple to state:

    • Daily: bank and card lines are coded, and vendor bills are entered the day they arrive.
    • Weekly: bank, card, and clearing accounts reconcile, and a controller clears the exception list.
    • Monthly, during the month: recurring journal entries, prepaid amortization, and payroll accruals are drafted before the period ends.

    The method overview describes how those rhythms fit into an engagement. This article focuses on the mechanics any finance team can copy.

    Why does a manual month-end close take two-plus weeks?

    A batch close starts every task on the same day, after the month ends, and most of those tasks depend on each other. One accountant then works through the whole queue in sequence.

    Take the illustrative company. It posts 1,240 bank and card lines a month across 5 accounts, plus 85 vendor bills and 140 customer invoices. One staff accountant has about 6 productive hours a day for close work.

    In a batch close, all 88 hours of close work begin on business day 1. Dividing 88 hours by 6 hours a day gives 14.7 business days, or roughly three calendar weeks. Reviews then add another round of questions, because nobody looked at the ledger during the month.

    The delay comes from queueing, not from slow staff. Coding 1,240 lines cold also takes longer, since each unfamiliar charge needs research weeks after it posted.

    How does a continuous close differ from a traditional batch close?

    The difference is timing. Both approaches perform the same tasks; a continuous close runs most of them before month-end instead of after.

    Close taskBatch: hours after month-endContinuous: hours during monthContinuous: hours after month-end
    Code 1,240 bank and card lines41392
    Reconcile 5 bank and card accounts15123
    Tie out AP and AR subledgers1293
    Accruals, prepaids, deferred revenue1064
    Review, flux analysis, close packet1066
    Total887218

    The worked arithmetic shows the trade. The continuous version totals 72 plus 18, or 90 hours, against 88 for the batch. Two extra hours pay for weekly reviews. After month-end, though, the remaining work falls from 88 hours to 18, and 18 divided by 6 is 3.0 business days.

    What does that look like on the close calendar?

    With 3.0 days of tie-out left, the books close on business day 5. Day 4 goes to controller review, and day 5 to the packet.

    The daily load during the month stays modest. Coding 39 hours across 21 business days works out to about 1.9 hours a day, or roughly 59 lines. That fits inside a normal week without overtime.

    For the sequence of gates inside those five days, the 5-day close calendar lays out each day. To see where a given company sits today, compare it against the close benchmarks by company size.

    Which close tasks move to daily and weekly cadences?

    Move any task whose inputs arrive during the month. Keep at month-end only the tasks that need the final balance or the cutoff date.

    • Daily: transaction coding, bill entry into Bill.com or the ledger, and deposit matching against open invoices.
    • Weekly: bank and card reconciliations, clearing-account sweeps, AR aging review, and the controller’s exception list.
    • Mid-month: drafting recurring entries, rolling prepaid and fixed-asset schedules, and updating deferred revenue under ASC 606.
    • Month-end only: cutoff, final accruals, intercompany and payroll true-ups, flux review, and sign-off.

    Weekly reconciliation is the anchor. It caps any unexplained item at seven days old, which keeps research short. The trade-offs of each cadence are covered in how often to reconcile accounts.

    Does closing faster sacrifice accuracy?

    No, provided review moves forward with the work. Accuracy depends on who checks the ledger and how often, while speed depends on when the work starts.

    Public-company rules show that speed and rigor are separate settings. The SEC’s Form 10-Q instructions set two quarterly filing windows. The largest filers have “40 days after the end of the fiscal quarter for large accelerated filers and accelerated filers.” Every other registrant has “45 days after the end of the fiscal quarter for all other registrants.” Those windows cover auditor review and disclosure drafting, which a private monthly close does not need.

    A continuous close adds checkpoints instead of removing them. In the example, four weekly reviews catch miscoded lines while the context is fresh. Aaron Ressel reviews every close packet before it ships, so the final sign-off is unchanged.

    What tooling does a continuous close require?

    It requires a cloud ledger with bank feeds, a bill-pay tool, and written schedules. It does not require an enterprise system.

    • A general ledger with live bank feeds: QuickBooks Online, Xero, or NetSuite.
    • A payables tool such as Bill.com, so bills enter the ledger on arrival.
    • Prepaid, accrual, and deferred revenue schedules kept current each month.
    • A shared close checklist with an owner and a due cadence on every line.

    Software improves the data; a team still runs the close. Puzzle, a platform Debit & Co. partners with, delivers categorized transactions quickly, and a controller turns that feed into reviewed books. Bank-feed setup across ledgers is covered in automating bank reconciliation.

    Can you run a continuous close in QuickBooks Online?

    Yes. Most single-entity companies can run the full method in QuickBooks Online with Bill.com alongside it.

    The ledger matters less than the cadence. A file with connected feeds, a clean chart of accounts, and documented coding rules supports daily work. Companies with several entities usually consolidate outside the ledger, which adds a day to the close calendar.

    What has to be true before a continuous close works?

    The books must be clean, the work must have an owner, and the procedures must be written down. Without those three, daily coding just moves the backlog forward.

    • A reconciled starting point. Prior periods must tie to bank and card statements.
    • Named owners. Each daily and weekly task needs one responsible person and one reviewer.
    • Documented rules. Coding conventions, accrual logic, and cutoff policy belong in a written Custom Playbook™.
    • Timely inputs. Receipts, approvals, and contract changes must reach accounting within days, not at quarter-end.

    A company that is months behind should finish a cleanup first. Starting a daily cadence on unreconciled history usually stalls within one cycle.

    Frequently asked questions

    What is a continuous close?

    A continuous close performs coding daily, reconciliations weekly, and review in weekly batches, so most of the ledger is tied out before month-end. In the worked example, only 18 of about 90 close hours remain after the period ends.

    Does a continuous close eliminate month-end entirely?

    No. Cutoff, final accruals, payroll and intercompany true-ups, flux review, and sign-off still happen after the period ends. They take about 3 business days instead of 15, and the packet ships on day 5.

    Can you do a continuous close in QuickBooks Online?

    Yes. A single-entity company with connected bank feeds, Bill.com for payables, a clean chart of accounts, and written coding rules can run the method in QuickBooks Online. Multi-entity groups usually consolidate outside the ledger.

    Does closing faster sacrifice accuracy?

    No, provided review moves forward with the work. Weekly controller reviews catch miscoded lines while context is fresh, and a final sign-off still happens before the close packet ships.

    What has to be true operationally before continuous close works?

    The books need a reconciled starting point, and every recurring task needs a named owner and reviewer. Coding and accrual rules must be written down, and source documents must reach accounting within days.

    Sources: U.S. Securities and Exchange Commission, Form 10-Q General Instructions. Worked example is illustrative.

  • Your First 90 Days With an Outsourced Accounting Firm: Onboarding, Cleanup, and the First Fast Close

    Your First 90 Days With an Outsourced Accounting Firm: Onboarding, Cleanup, and the First Fast Close

    The short answer: The first 90 days with an outsourced accounting firm run in 3 phases. Access and onboarding take days 1–14, cleanup and handoff days 15–60, and the first fast close days 61–90. In the worked example below, a file 7 months behind reaches a business-day-7 close by its third monthly close, down from day 16 on the first.

    • Grant access in week 1. Every missing login adds days to the cleanup, not to the firm’s calendar.
    • Cleanup comes before the recurring close; a close built on unreconciled months carries the old errors forward.
    • The prior bookkeeper’s handoff is a document list, not a phone call. Ask for it in writing.
    • Expect the first full monthly package around day 45–60, and a close inside 5–7 business days by the third monthly close.

    Last updated October 2026.

    Hiring the firm is the easy part. The first quarter decides whether the engagement produces trustworthy numbers or a second set of stale books. Most of what slows that quarter sits on the client side of the table.

    This guide sets out the 3 phases, the access and documents each one needs, and a worked timeline for a company 7 months behind. It also covers the handoff from a previous bookkeeper and what a realistic first close looks like.

    Open laptop and a blank sheet of paper on a wooden desk, representing the first weeks of an engagement with an outsourced accounting firm
    Photo by Pixel.la Free Stock Photos, Wikimedia Commons, CC0.

    How does onboarding with an outsourced accounting firm work?

    Onboarding with an outsourced accounting firm moves through access, cleanup, and a first close, in that order. Each phase has a defined output, and the next one cannot start cleanly until it lands.

    PhaseDaysClient providesFirm delivers
    1. Access and onboarding1–14Logins, prior returns, chart of accounts, a named contactWritten diagnostic with counts of unreconciled months and uncoded transactions
    2. Cleanup and handoff15–60Answers to open questions within 2 business daysEvery account reconciled through the cutoff month, suspense at $0.00
    3. First fast close61–90Month-end approvals and receipts on a set dateA monthly package on a committed business day

    The diagnostic at the end of phase 1 is the contract for phase 2. It turns “the books are a bit behind” into a count that can be scheduled.

    What access and documents does the client provide?

    The client provides system access, prior-year tax returns, and the documents that explain balances nobody can trace. Access granted in week 1 keeps the cleanup on schedule.

    A typical access list covers 6 systems. They are the general ledger (QuickBooks Online or Xero, as an accountant user), read-only bank and card portals, payroll, Bill.com or another payables tool, the payment processor, and the cap table. The firm also needs the last 2 filed returns, loan agreements, and any lease or customer contract above a set threshold.

    Tax access is a separate authorization. Per the IRS, Form 8821 lets a taxpayer “Authorize any individual, corporation, firm, organization, or partnership you designate to inspect and/or receive your confidential information verbally or in writing for the type of tax and the years or periods listed on the form.” With the notice-copy box checked, the firm can receive notices and transcripts without routing every letter through the founder.

    Access controls deserve their own review; our guide to outsourcing data security and SOC 2 lists the questions to ask.

    How much historical cleanup is typical, and how long does it take?

    Cleanup length depends on months behind and transaction volume, so it should be quoted from a diagnostic. A file 2 months behind can be current in 2–3 weeks; one 7–12 months behind usually needs 5–8 weeks.

    The diagnostic should name 4 figures, and those figures set the schedule:

    • The last month every account tied to a statement
    • The number of unreconciled account-months
    • The balance in Uncategorized or suspense
    • The count of uncoded transactions

    Cleanup ends when the proof exists, not when the calendar says so. A reasonable standard is every bank, card, and loan account reconciled to the statement through the cutoff month, with a schedule of dated adjusting entries. The full sequence appears in our catch-up bookkeeping guide, and the scope a firm should commit to is covered in what a QuickBooks cleanup service delivers.

    How does the handoff from a previous bookkeeper work?

    The handoff works best as a written request list with a deadline, sent before the prior bookkeeper’s last day. Verbal walkthroughs rarely survive the first reconciliation.

    Ask for 7 items in writing:

    • Admin transfer of the QuickBooks Online file
    • Reconciliation reports for each account
    • Open accrual and prepaid schedules
    • The fixed-asset and depreciation schedule
    • Unresolved vendor or customer disputes
    • Payroll and sales-tax filing calendars
    • Any login held in a personal name

    Ownership matters here. The file and every subscription should sit in the company’s name, because the records outlive any provider. The IRS rule reads: “Keep employment tax records for at least 4 years after the date that the tax becomes due or is paid, whichever is later.” General records run 3 years. The period rises to 6 years if unreported income exceeds 25% of the gross income shown.

    What does a 90-day onboarding timeline look like? A worked example

    Consider an illustrative services company with $6.2M in annual revenue. Its books are 7 months behind across 9 bank, card, and loan accounts, with 2,100 uncoded transactions and $48,300 in suspense.

    That is 9 accounts × 7 months = 63 account-months to reconcile. At a review pace of 350 coded transactions a week, the 2,100 transactions take 6 weeks. Cleanup therefore runs from day 15 to roughly day 57, inside the phase-2 window, and the first close opens inside the 90 days.

    CloseBusiness day deliveredMain constraint
    Month 1 (first close)Day 16New bank rules, first accrual review
    Month 2Day 11Late receipts from 2 approvers
    Month 3Day 7Steady state

    The close drops from day 16 to day 7, a cut of 9 business days, or 56% (9 ÷ 16 = 0.5625). The suspense balance falls from $48,300 to $0.00 before the first close opens.

    When should you expect the first complete monthly financial package?

    Expect the first complete package roughly 45–60 days in, once cleanup reaches the cutoff month. A package delivered sooner on unreconciled books is a draft, whatever its label.

    A complete package has 4 parts. They are a fully reconciled balance sheet, an accrual-basis income statement, a cash flow statement, and short variance commentary against the prior month. Founders raising capital may add a cash runway line and a headcount schedule.

    The first package also sets the format for every later one. Agree on the layout, the delivery day, and the sign-off owner before month 1 closes. The review sequence an outsourced team follows is set out in what month-end close looks like with an outsourced team.

    How quickly can the monthly close reach 5–7 business days?

    Most companies can reach a 5–7 business-day close by the third month after cleanup, provided approvals and receipts arrive on a fixed date. The constraint is usually the client calendar, not the firm’s capacity.

    Three habits drive the speed. Bank and card feeds are reconciled weekly rather than once a month. Accruals follow a standing schedule. Approvers commit to a cutoff, such as receipts by business day 2.

    Under the Continuous Close Method™, reconciliations run as transactions post, so month-end becomes review rather than catch-up. Aaron Ressel reviews each new client’s first close packet before it ships. Day-by-day sequencing appears in the five-day close calendar, and peer timing in month-end close benchmarks by company size.

    Once the close is steady, the recurring work follows the monthly bookkeeping routine after cleanup. The full scope of the service is described on our outsourced startup bookkeeping page.

    Sources: IRS, About Form 8821, Tax Information Authorization; IRS, How long should I keep records?

    Frequently asked questions

    How does outsourcing bookkeeping and accounting work day to day?

    The firm works inside the company’s own QuickBooks Online or Xero file as an accountant user. Bank and card activity is coded and reconciled weekly, and open questions go to a named client contact. The month closes on a committed business day with a financial package and short variance notes.

    What happens during onboarding with an outsourced accounting firm?

    Onboarding runs in 3 phases over about 90 days. Access and a written diagnostic take days 1–14, cleanup and the prior bookkeeper’s handoff days 15–60, and the first fast close days 61–90. Each phase has a defined output before the next one starts.

    What access and documents does the client need to provide?

    Accountant-user access to the general ledger, read-only bank and card portals, payroll, payables, the payment processor, and the cap table. Add the last 2 filed tax returns, loan agreements, and material contracts. A signed Form 8821, with the notice-copy box checked, lets the firm receive IRS notices and transcripts.

    How long until the books are caught up and current?

    It depends on months behind and transaction volume. A file 2 months behind can be current in 2–3 weeks; one 7–12 months behind usually needs 5–8 weeks. A written diagnostic counting unreconciled account-months and uncoded transactions should set the schedule.

    How quickly can the monthly close get to 5–7 days?

    Most companies reach a 5–7 business-day close by the third month after cleanup. Weekly reconciliations, a standing accrual schedule, and a fixed receipt cutoff such as business day 2 do most of the work. In the worked example, the close fell from day 16 to day 7.

  • What Month-End Close Looks Like With an Outsourced Team: Timeline, Handoffs, and Sign-Off

    What Month-End Close Looks Like With an Outsourced Team: Timeline, Handoffs, and Sign-Off

    The short answer: An outsourced month-end close splits the work three ways. The client supplies inputs and decisions, the outsourced accountant prepares the books, and a controller reviews before anything is released. A healthy outsourced month-end close ships in 5 to 7 business days, and the slowest link is usually the client’s open-items reply time.

    • The client keeps legal responsibility for the books and taxes even when every entry is prepared outside the company.
    • Client inputs are due by business day 2: payroll registers, new contracts, approvals, and receipts the bank feed cannot explain.
    • In the worked example below, 3 slow answers out of 18 open items carry 46.2% of the unexplained dollars and push delivery back 3 business days.
    • Nothing reaches the owner until a second person has reviewed it, and the period locks after sign-off.

    Last updated October 2026.

    Handing the close to an outside team changes who types the entries. It does not change who answers for the numbers. Owners who miss that distinction tend to wait for statements that are actually waiting on them.

    The sections below map the ownership split, the inputs a client still owes, the handoff points across a real September 2026 calendar, and the review loop that runs before the package is released. A worked example shows how open-item response time moves the delivery date.

    Accountant typing at a desk keyboard while working through a month-end close
    Photo by Pixel.la, Wikimedia Commons, CC0.

    Who owns the month-end close when accounting is outsourced?

    The client owns the result, and the outsourced team owns the preparation and review. Responsibility for the books, and for the taxes they support, stays with the company.

    Federal guidance is explicit on the tax side. The IRS page on outsourcing payroll duties states that “the employer is ultimately responsible for the deposit and payment of federal tax liabilities.” The same logic governs the close. A firm can prepare every journal entry, yet the owner still approves the statements and answers to lenders, investors, and tax authorities.

    Records follow the same rule. IRS guidance on how long to keep records sets a general 3-year period for income tax support and at least 4 years for employment tax records. A sound engagement keeps the ledger, documents, and close workpapers in systems the client controls.

    What does the client still provide each month?

    The client provides the facts the bank feed cannot see, and those inputs are due by business day 2. Late inputs are the most common reason an outsourced close slips.

    • Payroll register and any off-cycle bonus or commission approvals for the month.
    • New or changed contracts, including customer terms that affect revenue timing and vendor agreements with prepaid or annual billing.
    • Unrecorded bills for work already received, so expenses land in the month they were incurred.
    • Receipts and explanations for card charges and transfers the team flags as unclear.
    • Decisions on write-offs, capitalization, and intercompany charges, which only management can make.

    Everything else, from bank reconciliation to accruals and schedules, belongs to the outsourced team.

    What does an outsourced month-end close timeline look like?

    For a September 2026 close, the work starts Thursday, October 1, and the reviewed package ships by Thursday, October 8, which is business day 6. Each day ends with a handoff to a named owner.

    Business dayDateWho holds the workHandoff at end of day
    1Thu, Oct 1Outsourced accountantBank and card feeds reconciled; open-items list started
    2Fri, Oct 2ClientPayroll register, contracts, receipts, and approvals delivered
    3Mon, Oct 5Outsourced accountantAccruals, prepaids, deferred revenue, and payroll entries posted
    4Tue, Oct 6Controller reviewerReview notes returned; client questions consolidated
    5Wed, Oct 7Client and accountantFinal answers received; review notes cleared
    6Thu, Oct 8Controller reviewerStatements and variance notes released; period locked

    Teams that reconcile weekly during the month compress days 1 and 3 sharply. That practice sits at the center of the Continuous Close Method™. For the internal mechanics of each day, see the five-day close calendar.

    How are open items handed between the client and the team?

    Through one shared open-items log, answered within one business day. Scattered email threads are where outsourced closes stall.

    Each log entry carries the date, amount, account, a specific question, and the owner. The accountant posts the question once, the client answers in the same row, and the reviewer closes it. A good log separates blocking items, which stop sign-off, from cleanup items, which can carry to next month with a note.

    Worked example. A $11M professional services company runs about 640 transactions a month. On October 2, the log holds 18 items totaling $47,300 of unexplained activity. The client answers 15 items within one business day; those total $25,450. Three items, worth $21,850, wait three business days.

    The arithmetic is lopsided. The late items are 3 ÷ 18 = 16.7% of the count, yet $21,850 ÷ $47,300 = 46.2% of the dollars. They are too large to leave in suspense, so sign-off moves from business day 6 to business day 9, and delivery slips from Thursday, October 8 into the following week.

    How does review and sign-off work before the client sees anything?

    Every package passes a second person before release. The preparer never approves their own work, and the period locks only after the client has the final version.

    The loop has three layers. The accountant prepares and ties each balance sheet account to a reconciliation or schedule. The controller reviews flux against the prior month and budget, then writes notes the preparer must clear. The owner receives the statements with plain-language variance notes and confirms nothing is missing. At Debit & Co., Aaron Ressel holds that controller review standard on close engagements.

    After sign-off, the period is locked in the ledger, whether QuickBooks Online or NetSuite, so posting requires an override. Any later change becomes a dated adjusting entry in the open month, so a board packet never silently changes after it is sent.

    How fast should an outsourced close be, and what is a red flag?

    Five to seven business days is a sound target for a single-entity company. Ventana Research found 58% of organizations closing the month within six business days in 2023, and our close benchmarks by company size show how the range widens with entities and volume.

    Speed alone proves little. The warning signs are structural:

    • Statements arrive after business day 15 for three months running.
    • No reviewer is named, or the preparer and reviewer are the same person.
    • Prior months reopen without a dated adjusting entry.
    • Suspense or uncategorized balances grow month over month.
    • The client cannot see the open-items log or the reconciliations.

    Two or more of these signs usually point to a process problem that more hours will not fix. The guide to fixing a broken month-end close covers that repair, and the outsourced controller service describes the review layer in practice.

    Frequently asked questions

    Who owns the month-end close when accounting is outsourced?

    The company owns the result and the outsourced team owns preparation and review. IRS guidance states that an employer remains ultimately responsible for federal tax deposits even when a third party handles them, and the same principle applies to the books the owner approves.

    What does the client still have to provide each month?

    By business day 2, the client provides the payroll register, new or changed contracts, unrecorded bills, receipts for flagged charges, and management decisions such as write-offs. These are facts a bank feed cannot capture, and late inputs are the most common reason an outsourced close slips.

    How long should an outsourced month-end close take?

    Five to seven business days is a sound target for a single-entity company, and 58% of organizations in Ventana Research’s 2023 study closed within six. For a September 2026 close, that means a reviewed package by Thursday, October 8, provided client answers arrive within one business day.

    How do you keep control when the close is outsourced?

    Keep the ledger and documents in systems the company controls, require a named reviewer separate from the preparer, and work from a shared open-items log you can see. Lock each period after sign-off so later changes appear as dated adjusting entries.

  • The Accounts Payable Month-End Close: Cutoffs, Accruals, and a Checklist That Holds Up

    The Accounts Payable Month-End Close: Cutoffs, Accruals, and a Checklist That Holds Up

    The short answer: The accounts payable month-end close runs on five controls: an invoice cutoff, accruals for costs received but not yet billed, a tie-out of the AP aging to the general ledger, a second-person review, and a period lock. In the worked example below, 23 late vendor invoices worth $58,740 would have overstated one month’s gross margin by 4.3 points.

    • Cutoff follows the date goods or services arrived, never the invoice date or the payment date.
    • An invoice capture deadline of business day 3 leaves two days for review inside a 5-day close.
    • The AP aging and the AP control account must agree to the dollar before the period locks.
    • Missed accruals distort two months: the close month looks too profitable and the next month too expensive.

    Last updated September 2026.

    Payables are where a month-end close quietly loses accuracy. Revenue gets scrutiny because owners watch it. Vendor costs arrive on the vendor’s schedule, often days or weeks after the work was done, and a close that books only the bills in hand will understate expenses every single month.

    The fix is procedural. The sections below cover how to set the cutoff, when to book an accrual, how to reconcile the aging report, and how long the AP portion of the close should take. A worked example runs the arithmetic on a mid-sized distributor.

    Accountant marking up a financial report beside a calculator while reviewing vendor costs at month end
    Photo by asawin via pxhere, Wikimedia Commons, CC0.

    What are the steps in the accounts payable month-end close?

    Five steps, in order: capture every invoice by the cutoff, accrue what arrived without a bill, reconcile the aging to the ledger, review, and lock. Skipping the order produces a reconciled balance that is still incomplete.

    StepWhat it provesTarget day (5-day close)Owner
    1. Invoice capture and cutoffEvery bill for the month is enteredBusiness day 3AP clerk or bookkeeper
    2. Accruals for unbilled costsCosts incurred without an invoice are recordedBusiness day 3Staff accountant
    3. Aging-to-ledger tie-outThe subledger and the AP control account agreeBusiness day 4Staff accountant
    4. ReviewA second person has checked steps 1–3Business day 4Controller
    5. Period lockNo one can post into the closed monthBusiness day 5Controller

    The AP steps sit inside the wider sequence covered in the month-end close process, and they mirror the receivables side described in the accounts receivable month-end close.

    How do you set a vendor invoice cutoff at month end?

    Pick a business day, publish it to every approver, and book each invoice to the month the goods or services were received. The deadline controls data entry; the receipt date controls which period the cost belongs to.

    Business day 3 is the common choice for a 5-day close. For September 2026, that deadline falls on Monday, October 5, since September 30 is a Wednesday. Any invoice entered by then for September deliveries posts to September. Anything arriving later is handled through an accrual.

    The receipt date matters because the auditing standards treat completeness as its own assertion. PCAOB AS 1105 defines it as whether “all transactions and accounts that should be presented in the financial statements are so included.” Unrecorded payables are the textbook completeness failure, which is why auditors run a dedicated search for them.

    What is an AP accrual, and when should you book one?

    An AP accrual is a journal entry that records a cost incurred during the month before the vendor’s invoice arrives. Book one whenever goods or services were received by month-end and no bill was entered by the cutoff.

    Three sources produce most accruals:

    • Received, not invoiced. Inventory or materials on the receiving log with no matching bill.
    • Services billed in arrears. Contractors, freight, legal, and staffing firms that invoice after the month ends.
    • Recurring costs. Utilities, telecom, and usage-based software whose statements lag the service period.

    A materiality threshold keeps the work proportionate. Many companies accrue individual items of $2,500 or more and combine smaller ones into a single estimate. Set accruals to reverse on the first day of the next month, so the real invoice posts cleanly against the reversal instead of doubling the expense.

    Tax timing follows similar logic. IRS Publication 538 states that accrual-method businesses generally deduct an expense once the all-events test is met and economic performance has occurred.

    What happens when late vendor invoices are not accrued?

    Consider an illustrative wholesale distributor with $16.4M in annual revenue, or about $1,366,667 a month. Its cost of goods sold runs near 71% of revenue, so true gross margin is 29.0%.

    After the September close, 23 invoices for September deliveries arrive late, totaling $58,740. Nobody accrued them, so September cost of goods sold is understated by the full amount.

    The distortion is measurable. Dividing $58,740 by $1,366,667 gives 4.3 points of margin. September reports 33.3% gross margin instead of 29.0%.

    October then absorbs the same $58,740 and reports roughly 24.7%. The month-over-month swing is 8.6 points, and none of it reflects pricing or operations. A board reading those two months would draw the wrong conclusion twice. The same pattern appears in our breakdown of month-end close errors that distort margins.

    One accrual entry on business day 3 would have prevented both errors.

    How do you reconcile the AP aging report to the general ledger?

    Run the AP aging as of the last day of the month, compare its total to the AP control account balance, and explain every dollar of difference. The target variance is zero.

    Differences usually trace to three causes. A journal entry posted straight to the AP account without a vendor attached. A bill dated in one month but entered with a date in another. A vendor credit or prepayment recorded outside the subledger.

    In the distributor example, the aging totals $412,905 and the control account shows $427,318. The $14,413 gap resolves into two items: a $9,860 manual journal entry with no vendor, and a $4,553 bill dated October 2 but posted to September. Reclassing the first and correcting the date on the second brings the variance to zero.

    While the aging is open, scan the over-90-day column. Old unpaid balances are often duplicates, disputed bills, or payments recorded as expenses instead of against the bill. Cleaning up that history is covered in the step-by-step QuickBooks cleanup guide.

    How long should the AP portion of the close take?

    About three business days in a 5-day close. Invoice capture and accruals finish by business day 3, the tie-out and review land on business day 4, and the lock happens on business day 5.

    Speed depends on how early invoices reach the books. Automation through Bill.com or the payables module in QuickBooks Online or NetSuite captures bills when they arrive rather than at month-end, which shortens step 1. It does not replace the accrual review or the tie-out, since software only records the invoices it has received.

    The Continuous Close Method™ applies the same principle to the full ledger: bills are coded and matched as they land, so month-end holds review work instead of data entry. Aaron Ressel reviews the AP tie-out on each engagement before the period locks. The day-by-day schedule appears in the five-day close calendar, and ongoing ownership of these controls is part of Debit & Co.’s outsourced controller services.

    Frequently asked questions

    How do you handle vendor invoices that arrive after the cutoff?

    If the goods or services were received during the closed month, record an accrual for that month and let it reverse on day 1 of the next month. When the invoice arrives, enter it normally in the new month; the reversal offsets it, so the expense lands once, in the correct period. Invoices for costs incurred after month-end simply post to the new month.

    Do you need to reopen a closed month for a late invoice?

    Rarely. Reopening a locked period changes statements that owners and lenders may already have read. Most late invoices are handled through the accrual and reversal pattern instead. Reserve a reopen for material errors, and document the reason, the amount, and the approver when it happens.

    How does bill automation change the AP close?

    Tools such as Bill.com capture invoices on arrival, route approvals, and sync bills to the ledger, which moves data entry out of the close window. The controls stay the same. A person still has to accrue costs that arrived without a bill, tie the aging to the ledger, and review before the lock.

    How do I clear old accounts payable in QuickBooks?

    Start by reviewing each open bill older than 90 days. Match bills that were actually paid to the payment that should have closed them, void confirmed duplicates, and confirm disputed balances with the vendor. Any write-off of a genuine old balance should be dated in the current period, so prior-period statements stay intact.

    What should an AP month-end close checklist include?

    Invoice capture by a stated cutoff day, a receiving-log comparison for unbilled goods, an accrual list with amounts and reversal dates, an aging-to-ledger tie-out at zero variance, a review sign-off, and a period lock. Each line should carry an owner and a due day.

  • How a Fractional CFO or Controller Fixes a Broken Month-End Close

    How a Fractional CFO or Controller Fixes a Broken Month-End Close

    The short answer: A broken month-end close gets fixed in three moves: catch up the reconciliations, install a checklist with a named reviewer, and lock each period once it ships. A controller owns those mechanics; a fractional CFO owns what the close feeds. In the worked example below, a close landing on business day 19 moves to business day 6 within roughly 90 days.

    • Late books usually trace to missing reconciliations, cash-basis shortcuts, and an absent review step, rarely to a lack of effort.
    • A September close on business day 19 arrives October 27; on business day 6 it arrives October 8, nineteen calendar days sooner.
    • The May 2025 federal wage survey puts the median financial manager, the occupation that includes controllers, at $166,570 a year, or $13,881 a month before benefits.
    • Most companies under $20M need controller hours, not a controller headcount.

    Last updated September 2026.

    A month-end close is broken when the statements arrive too late to inform decisions, or arrive on time and then change. Both failures share a cause. Some part of the close depends on a person remembering to do it, and no one checks whether it happened. Adding hours to a broken process rarely helps, because the missing piece is structure.

    Outside finance help repairs that structure. The sections below separate what a controller fixes from what a fractional CFO fixes, then walk through a remediation with real arithmetic and a realistic timeline.

    Finance professional taking handwritten notes beside a laptop during a month-end review
    Photo by Shixart1985, Wikimedia Commons, CC BY 2.0.

    What does a broken month-end close look like?

    It looks like statements that arrive after the third week of the following month, or statements that reopen after the owner has read them. Either symptom means the numbers cannot carry a decision. The published benchmarks in our guide to month-end close benchmarks by company size put a typical close near six days.

    The warning signs are consistent across files. Bank and card accounts go unreconciled for months. An uncategorized or suspense account keeps growing. Payroll, rent, and vendor bills get recorded when paid instead of when incurred, so gross margin swings with the payment calendar. Adjusting entries appear after the board packet has gone out. No one signs off, because no one owns the review.

    Each sign is individually fixable. Together they describe a close that has no owner, which is the actual defect.

    Do you need a controller or a CFO to fix a broken month-end close?

    Usually a controller first. The controller role owns reconciliations, accruals, cutoff, and review, which are the mechanics that make a close late or wrong. A fractional CFO becomes the right hire once the numbers are dependable and the questions shift to cash planning, pricing, and board reporting. The table maps common symptoms to the role that resolves them.

    SymptomRoot causeWho fixes it
    Close lands after business day 15No checklist, no deadline per taskController
    Numbers change after sign-offNo review step, open prior periodsController
    Gross margin swings month to monthCash-basis expenses, missing accrualsController
    Suspense account keeps growingBank feed rules unmanagedController, with the bookkeeper
    Board asks questions the packet cannot answerNo variance analysis or forecastFractional CFO
    Cash surprises despite reported profitNo rolling cash forecastFractional CFO

    Companies with both problems need both roles, in sequence. A forecast built on unreconciled books inherits every error underneath it.

    How does an outside controller fix a late close?

    An outside controller follows a fixed sequence: diagnose, catch up, standardize, review, and lock. The order matters, because a checklist installed on unreconciled books only produces faster wrong answers.

    1. Diagnose. Tie every balance sheet account to external support and list each gap with its dollar value.
    2. Catch up. Reconcile every bank and card account through the latest month-end, clear the suspense account, and book missing accruals.
    3. Standardize. Write the close checklist with an owner and a due day for each task, following the structure of the month-end close process.
    4. Review. Add a second-person review of reconciliations and journal entries before statements leave the finance function.
    5. Lock. Set the closing date in QuickBooks Online or NetSuite once the packet ships, so a closed month stays closed.

    This is the scope of Debit & Co.’s outsourced controller services. Where years of history need rebuilding first, the work starts with catch-up bookkeeping.

    What does a close remediation look like in practice?

    Consider an illustrative $12.6M-revenue services company with 58 employees and one in-house bookkeeper. Its close lands on business day 19. Only 2 of its 7 bank and card accounts are reconciled for the last 6 months. The suspense account holds $41,370 across 214 transactions, and 3 of the last 6 closes reopened after the owner had read them.

    The catch-up workload is countable. Five unreconciled accounts across 6 months is 5 × 6 = 30 reconciliations. Clearing $41,370 across 214 transactions averages about $193 per item, so the work is volume, not a single large error.

    Timing makes the case for the fix. September 2026 closes on business day 19 on October 27. The same close on business day 6 lands October 8, nineteen calendar days sooner. Across a year, that returns roughly 19 × 12 = 228 days of earlier visibility into results.

    The reopen rate carries equal weight. Three reopened closes out of 6 is 50%, which means half of every month’s statements should not have been trusted when first delivered.

    How fast can an outside team get a late close back on schedule?

    Roughly 90 days for a file like the one above, assuming the history is recoverable from bank statements and source documents. Speed arrives in stages, because each close under the new checklist exposes the next bottleneck.

    • Weeks 1–2: diagnosis and the gap list, with dollar values attached.
    • Weeks 3–6: the 30 catch-up reconciliations, suspense cleared to $0, accruals booked for open months.
    • Month 2: the first checklist close, targeting business day 12.
    • Month 3: business day 8, then business day 6, with zero adjusting entries after sign-off.

    Files missing source documents, or carrying multiple entities, take longer. The day-by-day version of the destination sits in the five-day close calendar.

    What does close remediation cost compared to hiring in-house?

    The comparison that matters is hours needed, not headcount. The Bureau of Labor Statistics reports a median annual wage of $166,570 for financial managers as of May 2025, the occupation that includes controllers. That equals $13,881 a month in wages alone, before benefits, payroll taxes, and recruiting. The same survey puts accountants and auditors at a median of $83,680, or $6,973 a month.

    A full-time schedule is 2,080 hours a year, or about 173 hours a month. A company whose close needs 30 controller hours a month uses 30 ÷ 173 = 17% of that schedule. Hiring a full-time controller to cover 17% utilization buys capacity the company cannot use.

    Fractional rates run higher per hour than salary, so the math favors outsourcing only while the need stays part-time. Once controller work passes roughly half of a full schedule, an in-house hire deserves a serious look.

    What keeps a repaired month-end close from breaking again?

    Ownership, review, and a locked calendar. The close breaks again the moment reconciliations slip back to month-end or the review step gets skipped under deadline pressure.

    The Continuous Close Method™ addresses both. Reconciliations run as transactions land, so month-end holds review work instead of catch-up work, and the close finishes inside 5–7 business days. Kevin Cahill reviews the first three post-remediation closes on each engagement before the file moves to its steady monthly rhythm.

    Once the close holds for a quarter, the finance function can move up the stack to forecasting and board reporting, the work covered by outsourced CFO services.

    Frequently asked questions

    Can a fractional CFO help with the month-end close?

    Yes, although the close itself is controller work. A fractional CFO diagnoses why statements arrive late or change after delivery, then directs a controller to fix reconciliations, accruals, cutoff, and review. The CFO’s own contribution starts once the numbers are dependable: forecasting, variance analysis, and board reporting built on a close that no longer reopens.

    Do you need a controller or a CFO to fix late books?

    Late books are a controller problem first. Missing reconciliations, cash-basis expenses, and an absent review step are close mechanics, and the controller role owns them. A CFO adds value once the books are current and the questions move to cash planning and strategy. Companies with both problems should fix the close before building the forecast.

    What does monthly close support from an outsourced team include?

    Bank and card reconciliations, accruals and cutoff, suspense account clearing, a written close checklist with owners and due days, a second-person review of journal entries, and a locked closing date once statements ship. The deliverable is a close packet on a fixed business day, typically inside 5–7 business days once the file is current.

    How fast can an outside team get a late close back on schedule?

    About 90 days for a typical single-entity file with recoverable history. The first two weeks diagnose the gaps, weeks three through six clear the catch-up reconciliations, month two targets business day 12, and month three reaches business day 6. Missing source documents or multiple entities extend the timeline.

    What does close remediation cost compared to hiring in-house?

    The May 2025 federal wage survey puts the median financial manager, the occupation that includes controllers, at $166,570 a year, or $13,881 a month before benefits. A close needing 30 controller hours a month uses 17% of a 173-hour schedule. Outsourcing wins while the need stays part-time; past roughly half a schedule, an in-house hire deserves a look.

  • How to Automate Bank Reconciliation With Bank Feeds in QuickBooks Online and NetSuite

    How to Automate Bank Reconciliation With Bank Feeds in QuickBooks Online and NetSuite

    The short answer: To automate bank reconciliation, connect a bank feed, let matching rules clear recurring transactions, and reserve human judgment for exceptions and the statement tie-out. In the five-account model below, that division of labour reduces monthly reconciliation time from 36.5 hours to 19.0.

    • Matching rules and suggestions clear 1,212 of 1,460 monthly statement lines, an 83.0% automated share that leaves 248 exceptions requiring investigation.
    • The 17.5 hours recovered each month are worth $609 at a $34.80 loaded clerk rate, or $7,308 annually.
    • NetSuite’s auto-created transactions remain outside the general ledger until someone submits them.
    • A bank feed is a copy of institutional data. The statement’s ending balance remains the test every automated month must satisfy.
    • PCAOB AS 2201 lets auditors forgo retesting an unchanged automated control when IT general controls are effective, so rule edits need documentation.

    Last updated September 2026.

    Bank feed automation eliminates the data entry inside reconciliation. Data entry was never the control. The control is documented proof that every statement line exists in the ledger, carries the correct classification, and aggregates to the institution’s ending balance.

    The analysis below follows a modelled $22M B2B services company operating two checking accounts, one payroll account, and two corporate credit cards. It generates roughly 1,460 statement lines monthly, and the operative question is which of those lines still require human attention in QuickBooks Online or NetSuite.

    A person holding a payment card beside an open laptop at a bright home office desk
    Photo by Shixart1985, Wikimedia Commons, CC BY 2.0.

    How do you automate bank reconciliation?

    Automation works in three layers: a feed that imports statement lines, rules that match or categorize recurring activity, and a review procedure for everything the rules cannot place. Each layer absorbs work from the layer beneath it.

    1. Connect the feed. Map each bank and card account to exactly one ledger account. Begin the import after the last reconciled statement date, so previously cleared activity never duplicates.
    2. Write rules for recurring activity. Rent, payroll funding, software subscriptions, and processor deposits recur with predictable payees and amounts.
    3. Match against open items. Customer payments and vendor bills already recorded in the ledger should match their bank lines rather than generate duplicate entries.
    4. Work the exceptions weekly. Unmatched lines deteriorate quickly, because the context behind each one fades with every week of inattention.
    5. Tie out to the statement. The month closes when the ledger balance equals the statement’s ending balance, adjusted for timing items, exactly as in a manual bank reconciliation worked example.

    Debit & Co. performs step four on a weekly rhythm under the Continuous Close Method™, which leaves month-end with a brief confirmation instead of an accumulated backlog.

    How do bank feeds differ between QuickBooks Online and NetSuite?

    Both import statement lines automatically. They differ in how far the software proceeds without human approval, and that difference determines where review effort belongs.

    LedgerHow lines arriveWhat automates the matchWhat still needs a person
    QuickBooks OnlineConnected bank feedBank rules for recurring transactionsLines no rule covers, plus the rule set itself
    NetSuiteBank Feeds SuiteApp, daily automatic import, or file uploadIntelligent Transaction Matching: matching rules and auto-create rulesLines with two or more possible matches

    The practical difference concerns timing. In NetSuite, substantial review precedes posting to the general ledger.

    How much of a reconciliation can rules and matching clear?

    In this model, 83.0% of monthly lines, which reduces the workload from 36.5 hours to 19.0. The rates below are illustrative assumptions for a five-account company, not a published industry benchmark.

    1. Manual baseline. 1,460 lines × 1.5 minutes = 2,190 minutes, or 36.5 hours monthly.
    2. Automated share. Rules and matching clear 1,212 lines, and 1,212 ÷ 1,460 = 83.0%.
    3. Exception queue. The remaining 248 lines × 3.5 minutes = 868 minutes, or 14.5 hours.
    4. Sample review. Reviewing a 10% sample of automatically cleared lines, 121 lines at 1 minute each, adds 2.0 hours.
    5. Tie-out and rule maintenance. Statement tie-outs across five accounts, plus rule modifications, add 2.5 hours.
    6. Net saving. 36.5 − 19.0 = 17.5 hours. At the $34.80 loaded clerk rate, the recovered time is worth $609 monthly and $7,308 annually.

    Each exception consumes more time than a manually matched line, because exceptions are, by definition, the difficult transactions. Automation removes the routine 83% and concentrates professional judgment on the remainder.

    Are bank feed auto-matches reliable enough to trust?

    Trust them for clerical accuracy and verify them for classification. A rule can match the correct amount to the correct payee and still post it to the wrong account every month.

    NetSuite keeps a person in control. Oracle’s documentation on Intelligent Transaction Matching states: “If a rule finds two or more possible matches, NetSuite can’t choose one.” Auto-created transactions “do not impact your general ledger account until you submit them on the Match Bank Data page.”

    No ledger design eliminates the statement test. Feeds depend on connections, and connections fail. The institution’s ending balance reflects every posted item regardless.

    What still needs human review in an automated reconciliation?

    Five categories resist automation in any ledger, and together they account for most of the 248 exceptions in the model above.

    • Transfers between owned accounts. Each side appears in a different feed, and a rule that categorizes both sides as income and expense doubles reported activity.
    • Net processor deposits. A card processor deposit arrives net of fees and refunds, so it rarely corresponds to any individual invoice.
    • Payments without remittance detail. One customer wire covering three invoices matches none of them on amount alone.
    • New payees. No rule exists yet, and the first classification decision becomes the template for every subsequent rule.
    • Stale reconciling items. Outstanding checks and deposits in transit require someone to determine when a timing difference has become an error.

    The statement itself also requires a custodian. IRS Publication 583 lists account statements among the documents that support business expenses. Records supporting a deduction must be retained “until the period of limitations for that return runs out.” Download and archive each monthly statement, whatever the feed displays.

    How should bank rules be controlled once they run unattended?

    Treat each rule as an automated control: approved before activation, documented whenever it changes, and reviewed on a fixed schedule.

    Auditing standards already operate this way. PCAOB AS 2201 notes that entirely automated application controls “are generally not subject to breakdowns due to human failure,” which permits a benchmarking strategy. Under paragraph B29, an auditor may conclude such a control remains effective without repeating the prior year’s tests.

    That conclusion requires effective general controls over program changes, access, and computer operations, plus verification that the control has not changed since its baseline. The evidence needed depends partly on “the strength of the company’s program change controls.”

    Skipping the change log carries a measurable price. A rule that classifies a $2,340 monthly software charge as cost of revenue instead of operating expense misstates gross margin by $16,380 over seven months, with every line reconciled.

    Aaron Ressel’s review of a client rule set begins with the change log, because a match rate reveals nothing about where matched transactions landed. Frequency matters as well: how often reconciliation runs determines how long a defective rule can post before anyone notices.

    Frequently asked questions

    How do you link bank accounts in QuickBooks Online?

    Connect each account from the ledger’s banking settings using the institution’s own credentials, then map it to a single ledger account. Set the first download to begin after the last reconciled statement date, so previously cleared activity does not import twice. Confirm the first month against the statement before writing any rules.

    Can bank reconciliation be fully automated?

    Matching can approach full automation; reconciliation cannot. Rules and matching cleared 83.0% of lines in the model above, yet transfers, net processor deposits, unremitted payments, and stale items still required a person. The ending-balance tie-out and the review of rule modifications should remain with a person, whichever ledger holds the feed.

    What is the difference between a bank feed and a bank statement?

    A bank feed is a data connection that delivers transaction lines into the ledger. The bank statement is the institution’s official record of the period, with an opening balance, every posted item, and an ending balance. Reconciliation tests the ledger against the statement, because only the statement carries the institution’s ending figure.

    How often should bank rules be reviewed?

    Review each rule modification when it is made, and the complete rule set every quarter. A quarterly review identifies payees whose amounts changed, rules that no longer match anything, and loose conditions that capture unrelated transactions. In the model above, rule maintenance and statement tie-outs together require 2.5 hours monthly.

    Does automated reconciliation work for credit card and payment processor accounts?

    Credit cards automate well, because each charge posts as one line with an identifiable payee. Processor accounts are harder. Deposits arrive net of fees, refunds, and chargebacks, so one bank line must be split into gross sales and fees. A person should confirm that split against the processor’s settlement report each month.

  • Should You Outsource Bank Reconciliation? What Reconciliation Services Actually Do

    Should You Outsource Bank Reconciliation? What Reconciliation Services Actually Do

    The short answer: Outsourced bank reconciliation services take the monthly tick-and-tie off an internal calendar and return a closed, reviewed ledger. The decision rarely turns on the wage line. For the $9.4M distribution company modelled below, the reconciliation workload itself consumes $8,352 of loaded labour annually, while the smallest hire that can perform it costs $36,192.

    • Bookkeeping, accounting, and auditing clerks earned a median $24.36 an hour as of May 2025. Loaded for benefits at the June 2026 reference-period federal wage share, the rate approaches $34.80.
    • The workload is 20.0 hours a month. A part-time hire at 20 hours a week bills 86.7, so 76.9% of the paid time addresses something else.
    • A fixed monthly engagement at $1,150 costs $13,800 a year: $5,448 above the isolated workload, $22,392 beneath the smallest practical appointment.
    • Federal projections show the clerk occupation contracting 6% between 2025 and 2035, against roughly 144,100 openings a year driven by replacement.
    • Bank access should be read-only, and the provider holding it should produce a SOC 2 report across the five trust services categories.

    Last updated September 2026.

    Reconciliation is the one close procedure that cannot be deferred. Every downstream figure depends upon it, and no report constructed atop an unreconciled account withstands scrutiny. The procedure is repetitive, unglamorous, and easily postponed whenever the person performing it holds four other responsibilities.

    That combination is what pushes the question outward. The analysis below follows a $9.4M distribution company running five accounts on net-45 terms: what the obligation consumes internally, what an external provider assumes, and where the internal answer still wins.

    A bookkeeper annotating a worksheet by hand while operating a desk calculator
    Photo via Pexels, free for commercial use.

    What do outsourced bank reconciliation services actually do?

    They own the match, the exception queue, and the sign-off. The deliverable is a reconciled account with every variance explained, not a transaction feed.

    Scope divides into four repeating obligations. Each one carries a completion date, and each one belongs to the firm rather than to an internal calendar.

    1. Statement matching. Every line on the bank statement ties to a ledger entry, across operating, payroll, and reserve accounts.
    2. Credit card and processor settlement. Gross sales, fees, chargebacks, and net deposits settle separately. Processor activity is where most ledgers deteriorate.
    3. Exception resolution. Stale checks, duplicate entries, and unidentified deposits are investigated and cleared rather than deferred.
    4. Reviewed sign-off. A second reviewer confirms the completed work before it feeds the month-end close process.

    That fourth obligation separates a service from an errand. Debit & Co. runs it through the Continuous Close Method™, so exceptions surface weekly instead of accumulating until the statement arrives.

    What does the reconciliation workload cost in-house?

    Roughly $8,352 a year in loaded labour for this organization, substantially beneath what most owners estimate and substantially beneath what any individual hire can deliver.

    Begin with the published median. The Bureau of Labor Statistics reports that bookkeeping, accounting, and auditing clerks earned a median $24.36 an hour as of May 2025, or $50,670 a year.

    Wages alone understate the outlay. BLS published its June 2026 reference-period figures on September 9, 2026, in release USDL-26-1494. For private industry workers it states: “Wages and salaries averaged $32.82 and accounted for 70.0 percent of employer costs, while benefit costs averaged $14.07.” Total compensation reached $46.89 an hour.

    That share is economy-wide rather than occupational, so applying it to the median approximates the internal rate. The approximation remains defensible, and labelling it costs nothing.

    1. Loaded hourly rate. $24.36 ÷ 0.700 = $34.80 an hour.
    2. Monthly workload expenditure. 20.0 hours × $34.80 = $696.00.
    3. Annualized expenditure. $696.00 × 12 = $8,352.

    Why can an $8,352 task cost $36,192 to staff?

    Because 20 hours a month is not a job. The smallest hire that reliably covers the work is a part-time clerk at 20 hours a week, and that individual bills 86.7 hours a month whether or not the matching workload fills them.

    Staffing modelLoaded rateHours/monthMonthlyAnnual
    Reconciliation workload, isolated$34.8020.0$696$8,352
    Part-time clerk, 20 hrs/week$34.8086.7$3,016$36,192
    Owner absorbs the task$96.1520.0$1,923$23,076
    Outsourced fixed engagementFlat fee20.0$1,150$13,800

    The second row is the honest comparison. Purchasing $8,352 of verification costs $36,192, leaving $27,840 of compensated time requiring alternative work. Organizations genuinely holding that alternative work should hire. Organizations without it are purchasing idle capacity.

    The third row is the common default and the expensive one. A $200,000 owner package divides to $96.15 an hour across 2,080 hours, so the founder performing the match forfeits $23,076 annually in displaced attention.

    What does outsourcing actually save?

    Against the smallest real hire, $22,392 a year. Measured against the isolated workload, nothing: the engagement runs $5,448 above unadorned labour expenditure.

    Both figures are accurate, and the second invites the legitimate argument. A provider charging $1,150 a month supplies three elements the wage line omits: a reviewer, coverage during absence, and a fixed completion date. Whether those elements justify $5,448 depends entirely on what an unreconciled month inflicts on the business.

    The labour market supplies the other half of the argument. BLS projects the clerk occupation will contract 6% between 2025 and 2035, a loss of about 85,600 positions against roughly 144,100 annual openings created by replacement. Hiring into a shrinking, replacement-driven occupation is slower and more expensive than the wage table implies.

    Is it safe to give an outside firm access to bank statements?

    Yes, under two conditions: access is read-only, and the provider can evidence its controls. Neither condition deserves acceptance on verbal assurance.

    Read-only entitlements are standard at every significant institution. A provider requires visibility into statements and posted activity. It never requires payment initiation, wire authority, or user administration, and granting those entitlements manufactures an exposure the engagement never needed.

    Evidence comes from a SOC 2 report. The AICPA is direct about why these exist, stating that CPAs use its SOC offerings to “provide assurance reports that provide users with valuable information that is needed to assess and address the risks associated with outsourcing services.” The report covers five trust services categories: security, availability, processing integrity, confidentiality, and privacy.

    Request the Type 2 report rather than Type 1. Type 1 describes controls at a single point in time; Type 2 tests whether they operated throughout a period, which is the determinative question for a recurring monthly engagement.

    When does keeping reconciliation in-house still win?

    When the hours are already bought, or when the account volume is small enough that the task disappears into an existing role.

    An organization whose full-time bookkeeper carries genuine spare capacity should not outsource the function. The marginal cost is close to zero, and fragmenting the ledger across two parties creates handoffs where none existed. Identical logic governs a single-account business beneath roughly 150 monthly transactions.

    Retention is the constraint organizations routinely overlook. IRS Publication 583 states that “[y]ou must keep your records as long as they may be needed for the administration of any provision of the Internal Revenue Code.” Employment tax records must be kept “for at least 4 years after the date the tax becomes due or is paid, whichever is later.” An external provider holding those records requires an exit provision returning them in a usable format.

    Aaron Ressel treats the reviewer, not the matcher, as the part worth buying, because an unreviewed reconciliation fails in the same silence as none whatsoever. That review only works against a clean starting ledger, which is why a properly worked reconciliation precedes any engagement worth signing.

    Frequently asked questions

    What are outsourced bank reconciliation services?

    They are a recurring engagement in which an external accounting practice matches every bank, credit card, and payment processor statement to the general ledger, investigates and clears exceptions, and signs off before the close proceeds. The deliverable is a reconciled account with variances explained, not a categorized transaction feed.

    How do you outsource the bank reconciliation process?

    Grant read-only access to each account, hand over the current chart of accounts and the last closed reconciliation, and agree a completion date relative to statement availability. The provider then works the exception queue and reports whatever it could not clear. Anticipate that the initial two cycles run long, because opening balances typically carry unresolved items from prior periods.

    Is it safe to give an outside firm access to bank statements?

    It is safe when access is read-only and the provider evidences its controls with a SOC 2 Type 2 report. View-only entitlements permit reconciliation without any capability to move money. Payment initiation, wire authority, and user administration should never be included, because the engagement requires none of them.

    What does outsourced reconciliation cost compared to in-house time?

    In the model above, a fixed engagement at $1,150 a month runs $13,800 a year against $8,352 of isolated loaded labour, a premium of $5,448. Measured against the smallest hire that can actually perform the work, a part-time clerk at $36,192, the engagement saves $22,392. Which comparison applies depends on whether the internal hours already exist.

    Does outsourced reconciliation include credit cards and payment processors?

    It should, and the scope document ought to name each account. Processor settlement is where ledgers most frequently deteriorate, because gross sales, processing fees, chargebacks, and the net deposit each post differently. Software including QuickBooks Online, NetSuite, and Puzzle can import those feeds cleanly. Interpreting the fee variance still requires a person, and reconciliation frequency determines how far that person falls behind.