Category: Cash visibility

  • Cash Flow Forecasting Tools for Startups: Spreadsheets, QBO Add-Ons, and When to Upgrade

    Cash Flow Forecasting Tools for Startups: Spreadsheets, QBO Add-Ons, and When to Upgrade

    The short answer: Cash flow forecasting tools for startups fall into three tiers: a spreadsheet, a forecasting app connected to QuickBooks Online or Xero, and a planning platform that runs scenarios across entities. A spreadsheet is usually enough until the weekly update takes more than about 4 hours or the company passes 2 entities. Below that line, the tool matters less than the books it reads.

    • Tier 1 is a spreadsheet: near-zero software cost, full control, and every update typed by hand.
    • Tier 2 is a ledger-connected app: actuals sync from the accounting file, so the update drops from hours to minutes.
    • Tier 3 is a planning platform: driver-based scenarios, multiple entities, and board-ready versions.
    • In the worked example below, a $400/mo app pays for itself once it saves about 4.2 hours of finance time a month.
    • No tool repairs a forecast built on unreconciled books. Fix the close first.

    Last updated October 2026.

    Choosing cash flow forecasting tools is mostly a question of timing. The same 13-week model can live in a spreadsheet, a connected app, or a planning platform. What changes is how much manual work each weekly update takes, and how many people can trust the result.

    This guide sorts the options into three tiers, lists the signals that a startup has outgrown its spreadsheet, and runs the cost math for one illustrative seed-stage company. The method itself is covered in our guide on how to build a cash flow forecast.
    Row of vintage mechanical adding machines with keyboards and paper-tape rollers on display before the computer era
    Before Computers, Adding Machines, via Wikimedia Commons, CC0.

    What are the main types of cash flow forecasting tools?

    There are three tiers. Each one adds automation and governance, and each one costs more to run.

    TierWhat it isHow actuals arriveTypical fitMain risk
    1. SpreadsheetExcel or Google Sheets model, usually a 13-week direct forecastExported and pasted by hand each week1 entity, 1–3 bank accounts, under about 300 transactions a monthBroken links, overwritten formulas, one person who understands it
    2. Ledger-connected appForecasting app synced to QuickBooks Online or XeroAutomatic sync from the accounting filePost-seed companies that update weekly and report monthlySyncs whatever the ledger holds, errors included
    3. Planning platformFP&A software with driver-based models and version controlSync from the ledger, payroll, and billing systems2 or more entities, a board that asks for scenarios, Series A and laterSetup time and a model too complex for the team to maintain

    The tiers overlap. Many Series A companies keep a spreadsheet for the weekly cash view and use a platform for the annual plan.

    Is a spreadsheet enough for startup cash forecasting?

    For most pre-seed and seed companies, yes. A spreadsheet handles one entity, a few bank accounts, and a weekly update without strain.

    Its strengths are control and transparency. Every formula is visible, and a fractional CFO can audit the logic in an afternoon. Its weakness is labor. Someone exports the bank activity, pastes it, re-codes it, and rolls the weeks forward, every week.

    That labor grows with volume, not with company age. A startup with 140 transactions a month can run a clean spreadsheet for years. One with 900 transactions a month and three payment processors will spend more time feeding the model than reading it.

    What forecasting tools connect to QuickBooks Online?

    Tier 2 and Tier 3 tools generally connect to QuickBooks Online, Xero, and NetSuite through an API link. That link replaces the weekly export.

    Ask four questions before buying any connected tool:

    • Sync depth: does it pull open bills and invoices, or only posted transactions? Open AP and AR drive the next 13 weeks.
    • Sync frequency: daily, hourly, or on demand? Weekly forecasting needs at least a daily refresh.
    • Method: does it support a direct, receipts-and-disbursements forecast, or only an indirect model built from the P&L?
    • Exit path: can the model and its history export to a spreadsheet if the company switches tools?

    The method question matters most for short horizons. Our comparison of direct vs. indirect cash flow forecasting explains why the direct method suits the 13-week view.

    When do you outgrow the spreadsheet model?

    When the weekly update takes longer than about 4 hours, or when the structure of the company outgrows one tab. Five signals mark the line.

    • The weekly update takes more than 4 hours, or about 17 hours a month.
    • The company runs 2 or more legal entities or bank relationships in more than one currency.
    • The board asks for base, downside, and extension cases every quarter.
    • More than one person edits the model, and nobody knows which version is current.
    • Forecast error on week-4 cash exceeds 10% for three months running.

    The last signal needs care. A forecast can miss because the tool is weak or because the inputs are late. Our guide to cash flow forecast accuracy shows how to measure the miss before deciding which problem to fix.

    What does it cost to upgrade from a spreadsheet?

    Less than it looks, once finance time is priced in. In the example below, a connected app costs $400/mo and saves 11 hours a month.

    Take a seed-stage SaaS company with $2.9M in annual recurring revenue, 22 employees, and about 620 transactions a month. Its controller spends 4.5 hours each week updating a spreadsheet forecast. A connected app at $400/mo, an illustrative price for this example, would cut that to 2 hours a week.

    LineSpreadsheetConnected app
    Weekly update time4.5 hours2 hours
    Monthly update time (× 4.33 weeks)19.5 hours8.7 hours
    Finance time at $95/hr$1,853/mo$827/mo
    Software cost$0/mo$400/mo
    Total monthly cost$1,853/mo$1,227/mo

    Run the arithmetic. The app saves 19.5 − 8.7 = 10.8 hours a month, worth 10.8 × $95 = $1,026. Net of the subscription, that is $626 a month, or $7,512 a year. Break-even sits at $400 ÷ $95 = 4.2 hours saved a month. A company whose update already takes under an hour a week gains little from the switch.

    What should you look for in a cash flow forecasting tool?

    Look for the features that cut manual work without hiding the logic. A tool that produces a forecast nobody can explain will not survive a board meeting.

    • Weekly buckets: a 13-week view by week, not only by month.
    • Variance tracking: forecast vs. actual stored for every past week.
    • Scenario copies: base, downside, and extension cases from one set of drivers.
    • Driver inputs: hires, price changes, and collection terms such as net-60 entered as assumptions.
    • Audit trail: who changed which assumption, and when.

    Scenario planning is where a Tier 3 platform earns its cost. Below that need, Tier 2 covers most of this list.

    Does better software fix a forecast built on messy books?

    No. A connected tool syncs the ledger as it stands, so uncategorized transactions and stale reconciliations flow straight into the forecast.

    The SBA’s guidance on managing business finances starts at the same point: “Make sure you maintain proper bookkeeping and have a basic knowledge of business finances.” The stakes are real. In the Federal Reserve Banks’ 2026 Report on Employer Firms, the most common reasons firms sought financing “were to meet operating expenses (56%) or to pursue an expansion or new opportunity (46%).”

    A forecast that misreads the cash position can send a company to its lender late. Our guide on why you can’t forecast cash from messy books covers the cleanup sequence.

    How does Debit & Co. choose forecasting tools for clients?

    The books come first, then the tool. Under the Continuous Close Method™, accounts are reconciled weekly, so the forecast reads balances that are days old, not weeks.

    Most seed clients stay on a spreadsheet 13-week model until the signals above appear. For clients on Puzzle, the ledger data arrives categorized; the team turns it into a reviewed close and a forecast. Kevin Cahill reviews the scenario assumptions before any board version ships. Our outsourced CFO services page outlines that forecasting work.

    Frequently asked questions

    Is a spreadsheet enough for startup cash forecasting?

    For most pre-seed and seed companies, yes. A spreadsheet handles one entity, a few bank accounts, and a weekly 13-week update. It becomes a burden when the update takes more than about 4 hours a week or the company adds a second entity.

    What forecasting tools connect to QuickBooks Online?

    Ledger-connected forecasting apps and FP&A planning platforms generally sync with QuickBooks Online, Xero, and NetSuite through an API link. Before buying, check whether the tool pulls open bills and invoices, how often it refreshes, and whether it supports a direct 13-week forecast.

    When do you outgrow the spreadsheet model?

    Common signals are a weekly update over 4 hours, 2 or more legal entities, a board that asks for quarterly scenarios, several people editing one file, and week-4 forecast error above 10% for three months running.

    What should you look for in a cash flow forecasting tool?

    Look for weekly buckets, stored forecast-vs-actual variance, scenario copies from one set of drivers, driver inputs such as hires and collection terms, and an audit trail of assumption changes. The logic should stay visible enough to explain to a board.

    Does better software fix a forecast built on messy books?

    No. A connected tool syncs the ledger as it stands, so uncategorized transactions and stale reconciliations flow into the forecast. Reconcile the books and fix the close before upgrading the forecasting tool.

    Sources: U.S. Small Business Administration, Manage your finances; Federal Reserve Banks, 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey. The company example, the $400/mo app price, and the $95/hr rate are illustrative.
  • Budget vs. Cash Flow Forecast: What Each Answers and Why Startups Need Both

    Budget vs. Cash Flow Forecast: What Each Answers and Why Startups Need Both

    The short answer: Budget vs cash flow forecast comes down to two questions. A budget plans 12 months of revenue and expenses on an accrual basis; a cash flow forecast predicts the bank balance week by week, usually 13 weeks ahead. In the worked example below, the October budget shows a $32,117 loss while the cash forecast shows $138,300 leaving the bank.

    • The budget is a spending plan and a scorecard. Set it once a year and measure the P&L against it.
    • The forecast is a liquidity tool. Update it weekly or monthly and measure the bank balance against it.
    • The two figures differ for three reasons: collection timing, annual prepayments, and capital purchases.
    • Pre-seed and seed companies should build the cash forecast first; the budget follows the first priced round.

    Last updated October 2026.

    Founders often treat the budget and the cash forecast as two versions of one spreadsheet. They are separate instruments. One measures performance against a plan, and the other measures whether payroll clears in week 9. A company with only a budget can hit its plan and still run short of cash.

    This guide compares the two documents, works through one month where they disagree by $106,183, and sets out which to build first and who should own each. All figures come from one illustrative B2B software company closing October 2026.

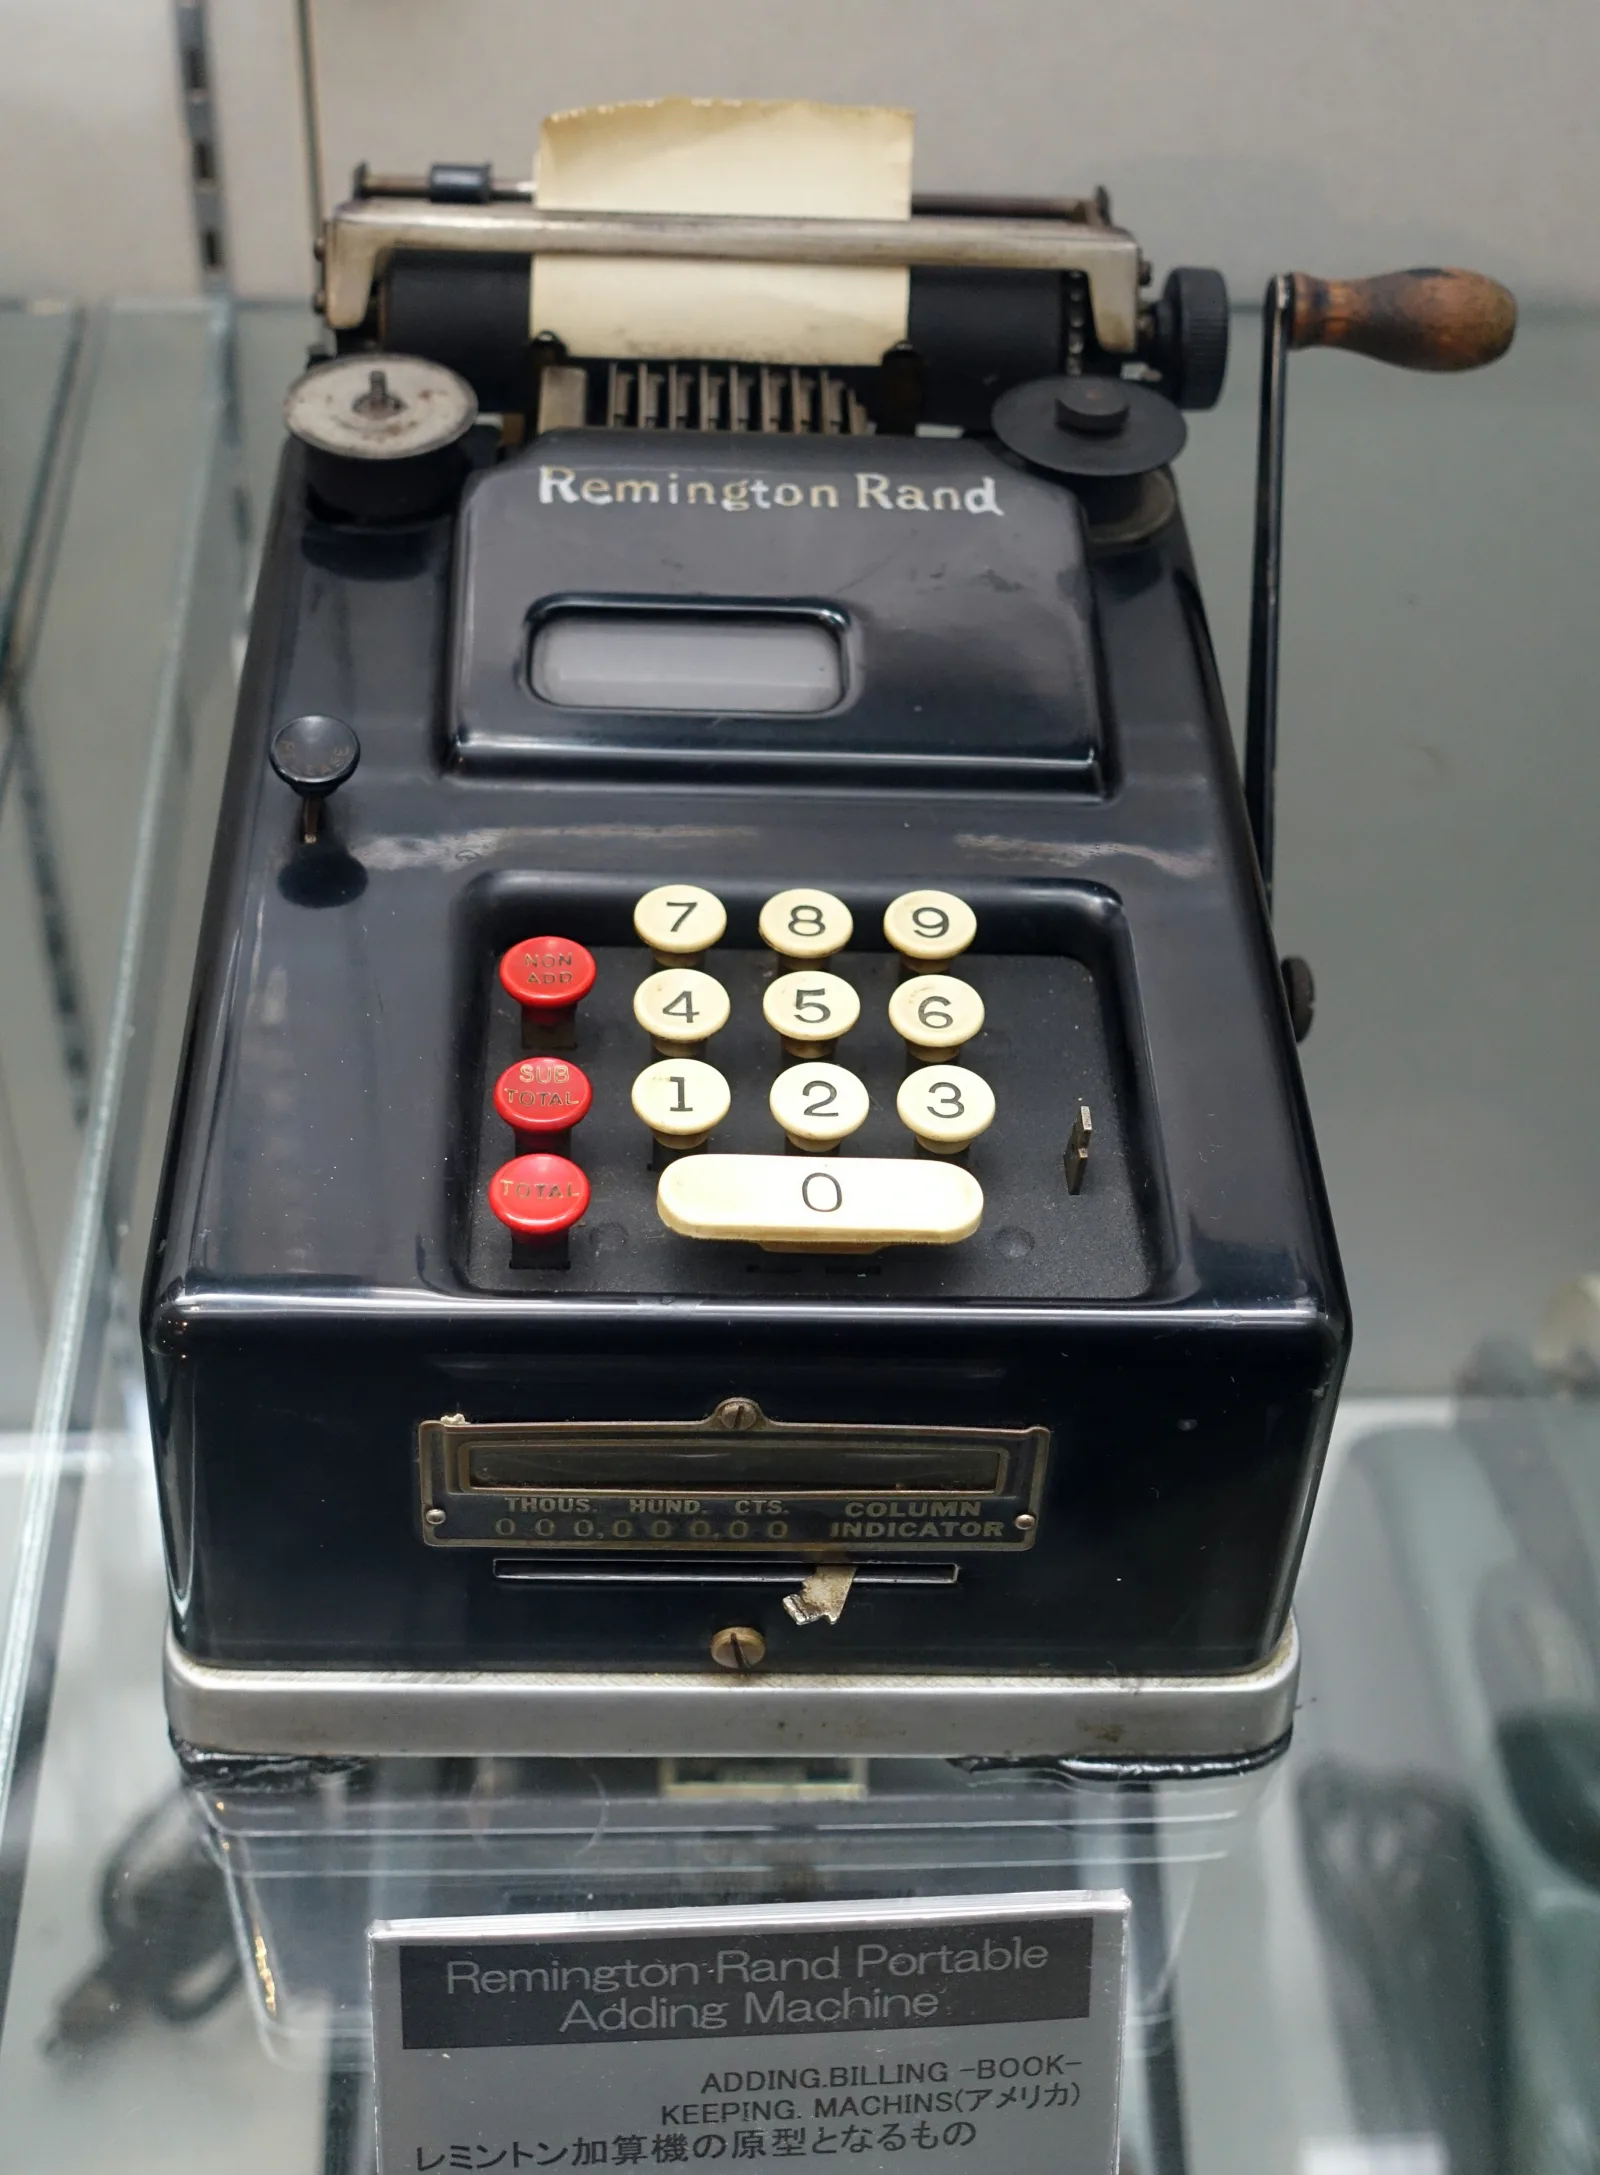
    Remington Rand mechanical adding machine with rows of number keys and a paper roll, displayed at a museum of science in Tokyo
    Photo by Daderot via Wikimedia Commons, CC0.

    Budget vs cash flow forecast: what is the difference?

    A budget is an accrual-basis plan of revenue and expenses for the fiscal year. A cash flow forecast is a cash-basis projection of receipts and payments, usually for the next 13 weeks to 12 months.

    The table sets out the differences that matter in practice.

    DimensionBudgetCash flow forecast
    Question answeredWhat do we plan to earn and spend?How much cash will we hold, and when?
    Accounting basisAccrual (GAAP P&L lines)Cash (bank receipts and payments)
    HorizonThe fiscal year, 12 months13 weeks rolling, often extended to 12–18 months
    Update frequencySet once; re-forecast quarterly at mostWeekly or monthly, always rolled forward
    GranularityMonthly, by department and GL accountWeekly, by receipt and payment type
    Measured againstActual P&L after the month-end closeActual bank balance
    Decisions it drivesSpending authority, hiring plan, board targetsPayroll coverage, runway, raise timing

    Our primer on what a cash flow forecast is covers the forecast’s components in detail. This article focuses on how the two documents fit together.

    What question does a budget answer?

    A budget answers how much the company intends to earn and spend, and whether it did. It is a plan that management commits to and the board approves.

    Its value comes from staying fixed. A department head with a $78,400/mo software and vendor line knows the spending limit without asking. After each close, the controller compares actual expenses to that line and explains the variance. If the budget changes every month, that comparison loses its meaning.

    Budgets are built on accrual accounting, so they follow GAAP timing. A $36,000 annual insurance premium appears as $3,000/mo. A $18,600 laptop purchase appears as $517/mo of depreciation over 36 months. Those conventions make the P&L comparable from month to month, and they also hide the dates on which cash leaves. Companies that tie spending to funding events can use milestone-based budgeting in place of a calendar-year plan.

    What question does a cash flow forecast answer?

    A cash flow forecast answers how much cash the company will hold at each future date. It exists to flag a shortfall early enough to act on it.

    The forecast is never fixed. Each week, actual receipts and payments replace the projections for the week just ended, and a new week is added at the end. The standard tool is the 13-week cash flow forecast, which shows every payroll run and every large vendor payment in the quarter ahead. Beyond 13 weeks, a rolling cash flow forecast extends the view monthly.

    Public companies face a version of this requirement in their filings. Regulation S-K Item 303 asks registrants to analyze their ability to generate and obtain adequate cash over the next 12 months, and separately beyond 12 months. Liquidity is assessed on its own, apart from results of operations.

    Why don’t the budget and the cash forecast agree?

    They disagree because accrual accounting and cash move on different calendars. Three items explain most of the gap: customer payment terms, annual prepayments, and capital purchases.

    The example company budgeted October 2026 as follows, with the cash forecast for the same month beside it.

    October 2026 lineBudget (accrual)Cash forecastGap
    Revenue vs. collections$286,500$231,400$55,100
    Payroll and benefits$214,800$214,800$0
    Software and vendors$78,400$78,400$0
    Rent$21,900$21,900$0
    Insurance$3,000$36,000$33,000
    Laptops (depreciation vs. purchase)$517$18,600$18,083
    Net result$32,117 loss$138,300 outflow$106,183

    Run the arithmetic. Budgeted expenses total $214,800 + $78,400 + $21,900 + $3,000 + $517 = $318,617, so the budgeted loss is $318,617 − $286,500 = $32,117. Cash out totals $214,800 + $78,400 + $21,900 + $36,000 + $18,600 = $369,700, so net cash flow is $231,400 − $369,700 = −$138,300.

    The bridge between the two is three lines. Collections trail revenue by $55,100 because customers on net-60 terms are paying August invoices. The insurance premium adds $33,000 because the full year is paid in October. The laptop purchase adds $18,083 because cash leaves on delivery while depreciation spreads the cost. The total is $55,100 + $33,000 + $18,083 = $106,183, which matches the gap exactly. The broader mechanics are in cash flow vs. revenue.

    Can an annual budget substitute for a cash flow forecast?

    No. A budget can show a small, on-plan loss in a month when cash outflow is four times larger, and the bank balance is the constraint that ends companies.

    In October, the budget reports a $32,117 loss. The bank reports $138,300 gone, or 4.3 times the budgeted figure. A founder who reads only the budget would see a quiet month. A founder who reads the forecast would see that October’s annual payments consume more than a typical month’s net burn, and would check that the following payroll is covered.

    The reverse substitution fails too. A cash forecast cannot tell a department head whether they overspent their plan, because it has no plan to compare against. Each document does one job.

    Which should a startup build first?

    Build the cash flow forecast first. Before the first priced round, the binding question is how many months of cash remain, and only the forecast answers it.

    A pre-seed or seed company with 6–15 employees usually needs three things: a 13-week cash forecast, a headcount plan, and a clean monthly close. The formal departmental budget becomes useful later, once department heads own spending lines and the board wants a plan to hold management against. That point usually arrives with a Series A and a headcount above 20.

    Stage (as of 2026)Cash flow forecastBudget
    Pre-seed / seed, under 15 people13-week, updated weeklyOne-page headcount and spending plan
    Series A, 15–50 people13-week plus 18-month monthlyAnnual budget by department, approved by the board
    Series B and later, 50+ people13-week plus rolling 24-monthAnnual budget with quarterly re-forecast

    How do the budget and forecast reconcile each month?

    After each close, compare the actual P&L to the budget and the actual bank balance to the forecast. Then bridge the two results with the timing items.

    • Step 1, budget variance: actual revenue and expense by line, against the budget, with a reason for any variance above $5,000 or 10%.
    • Step 2, forecast variance: actual ending cash against the forecast for that date, split into receipts and payments.
    • Step 3, the bridge: net income to net cash flow, through changes in accounts receivable, prepaid expenses, capital purchases, and deferred revenue.
    • Step 4, roll forward: update the next 13 weeks with what the close revealed, such as a customer who moved to net-90.

    The bridge in step 3 is the same logic as the indirect method on the cash flow statement. When it does not reconcile, the books usually contain a misclassified transaction, and the forecast built on those books inherits the error.

    Who maintains each document as the company grows?

    Finance owns both, though the roles split as the company scales. A controller typically maintains the cash forecast; a CFO owns the budget and presents it to the board.

    At seed stage, one person often does both, and that person is frequently the founder. By Series A, the controller updates the forecast weekly from reconciled bank data, while the CFO builds the annual budget with department heads in Q4. An outsourced CFO services engagement can cover both roles until the company can justify full-time hires.

    How does the Continuous Close Method™ keep both documents current?

    It keeps the ledger reconciled through the month, so budget variance and forecast variance are both available days after month end. Neither document waits on a cleanup.

    Debit & Co. reconciles bank and card accounts weekly, maintains prepaid and fixed asset schedules continuously, and posts collections against the forecast as they arrive. Kevin Cahill reviews the budget-to-cash bridge in each close packet before it goes to the client.

    Frequently asked questions

    What is the difference between a budget and a cash flow forecast?

    A budget is an accrual-basis plan of revenue and expenses for the fiscal year, used to set spending limits and measure the P&L. A cash flow forecast projects actual bank receipts and payments, usually 13 weeks to 12 months ahead, and is updated weekly or monthly to track liquidity.

    Can an annual budget substitute for a cash forecast?

    No. In the worked example, the October budget showed a $32,117 loss while $138,300 left the bank, 4.3 times more. Collection timing, an annual insurance premium, and a laptop purchase caused the gap. Only the cash forecast shows those dates.

    Which should a startup build first?

    The cash flow forecast. Before the first priced round, runway is the binding question, and a 13-week forecast plus a headcount plan covers most decisions. A departmental budget usually follows a Series A, once headcount passes about 20.

    How do the budget and forecast reconcile each month?

    After the close, compare actual P&L to budget and actual cash to forecast, then bridge net income to net cash flow through changes in receivables, prepaid expenses, capital purchases, and deferred revenue. In the example, three items explained a $106,183 gap.

    Who maintains each document as the company grows?

    At seed stage, often the founder maintains both. By Series A, a controller updates the cash forecast weekly from reconciled bank data, and a CFO owns the annual budget, builds it with department heads, and presents it to the board.

    Sources: 17 CFR 229.303(b)(1), Regulation S-K Item 303, Liquidity and capital resources. Worked example is illustrative.

  • Why Your Burn Rate Is Probably Wrong: The Calculation Mistakes That Distort Runway

    Why Your Burn Rate Is Probably Wrong: The Calculation Mistakes That Distort Runway

    The short answer: The most common burn rate mistakes come from reading burn off a single month of bank movement. In the worked example below, the bank says 17.3 months of runway, while the normalized books say 15.6 months.

    • A bank-balance change mixes timing, one-time items, and prepayments into the burn figure.
    • Net burn drives runway; gross burn shows the spending base. On the example file, the two readings differ by 6.5 months.
    • Annual prepayments move cash in one month and expense across twelve.
    • Recalculate after every close, and again after any hire, prepayment, or raise.

    Last updated October 2026.

    Burn rate looks like the simplest number in startup finance. Take last month’s cash decline and divide the bank balance by it. The problem is that a bank balance records when money moved, and burn is supposed to describe how fast the company consumes it.

    This guide covers the burn rate mistakes that distort runway most often, how to separate the bank view from the closed-books view, and what a corrected number tells investors. Every figure is an illustrative B2B software company in September 2026, so the arithmetic scales to another balance.

    Keyboard of a vintage Burroughs bookkeeping machine showing month keys and columns of digit keys
    Photo by Alan Levine via Flickr, Wikimedia Commons, CC0.

    What are the most common burn rate mistakes startups make?

    Five mistakes account for most distorted burn figures. Each one moves the reported number away from the true run rate by a few thousand to a few hundred thousand dollars.

    • One month as the whole story. A single month absorbs every timing quirk. A trailing three-month view smooths it.
    • Bank balance as the source. Uncleared payroll, card balances, and loan draws all change the bank line without changing operations.
    • Prepayments counted as burn. A $48,600 annual insurance premium paid in September is a $4,050/mo cost.
    • Customer prepayments counted as income. A $96,000 annual contract paid upfront flatters one month and lifts nothing afterward.
    • Gross burn quoted as net. Collections change the countdown, and the two figures answer different questions.

    Our guide to calculating burn rate and runway sets out the base formulas. The sections below show where those formulas break down.

    Should burn come from bank balance changes or from closed books?

    Start from reconciled books, and use the bank balance as a cross-check. The bank shows when cash moved, while a closed month shows what the cash movement meant.

    The two methods mirror a split the IRS describes. Publication 538 states that under the cash method, you “generally report income in the tax year you receive it.” Under the accrual method, you “generally report income in the tax year you earn it, regardless of when payment is received.” Burn sits between them: it is a cash measure, yet it only makes sense once each cash movement is classified.

    Four classification gaps appear most often in the raw bank figure:

    • Payroll that clears on the second of the next month.
    • Corporate card spend that has not yet been paid.
    • Debt or equity inflows that reduce the apparent decline.
    • Transfers between a company’s own accounts, counted twice.

    A reconciled ledger removes all four before the division happens. The related question of why profit and cash disagree is covered in cash flow vs. revenue.

    How do one-time items and annual prepayments distort burn?

    They shift cash into a single month that belongs to twelve months, or to none. The result is a burn figure that is too high one month and too low the next.

    In September 2026, the example company’s bank balance fell from $2,055,150 to $1,942,600, a decline of $112,550. That figure includes three items that do not describe the run rate:

    September 2026 itemCash effect in bankRun-rate treatmentAdjustment to burn
    Bank-balance net burn$112,550Starting point$112,550
    Annual insurance premium paid$48,600 out$4,050/mo ($48,600 ÷ 12)($44,550)
    One-time legal fee for a financing$31,200 outExcluded from run rate($31,200)
    Annual customer contract paid upfront$96,000 in$8,000/mo ($96,000 ÷ 12)$88,000
    Run-rate net burn$124,800

    The bank understated burn by $12,250, or 10.9%, because the upfront customer payment outweighed the two outflows. The legal fee still left the bank, so it stays in the cash balance and out of the monthly pace.

    Why does gross vs net burn change the runway answer?

    Net burn drives the runway countdown because collections offset spending. Gross burn measures the cost base, which is what a founder can cut.

    The example company spends $214,800/mo and collects $90,000/mo, which leaves net burn of $124,800/mo. Runway on gross burn would read $1,942,600 ÷ $214,800 = 9.0 months. Runway on net burn reads $1,942,600 ÷ $124,800 = 15.6 months. A deck that shows the 15.6-month figure under a gross-burn label invites a diligence question.

    Cash on hand needs the same care. Subtract obligations already incurred and due within 30 days, such as a $41,900 corporate card balance and $27,300 of payroll taxes. Available cash falls to $1,873,400, and runway to 15.0 months. Label which version the board sees.

    What does your burn rate really tell investors?

    Burn tells investors how much time the next milestone has. It also shows whether management knows its own numbers, which is the first thing a diligence review tests.

    Take a company that needs six months of cash in the bank when it opens a raise. On the bank figure, it has 17.3 − 6 = 11.3 months to reach its milestone. On the normalized figure, it has 15.6 − 6 = 9.6 months. That 1.7-month gap decides whether the milestone lands before the raise or after it.

    A burn rate also shapes outcomes through sequence. A founder who knows the true run rate can cut, delay a hire, or start the raise early. One who relies on the flattering number finds out a quarter late. Investors reviewing a data room reconcile the stated burn to the bank and the ledger, so a number that does not tie out costs credibility.

    How often should you recalculate burn and runway?

    Recalculate after every close, and again after any event that moves cash by more than a normal month. For most startups, that means monthly plus triggers.

    • Weekly: a directional bank check, labelled unreconciled.
    • Monthly: a full recalculation from the closed books, using the trailing three-month average.
    • On events: a new hire, an annual prepayment, a debt draw, or a raise.

    Use the weekly figure to spot problems and the monthly figure to report them. A 13-week cash flow forecast carries the same logic forward, and the comparison of runway and profit explains which metric leads in year one.

    How does a continuous close keep burn honest?

    A continuous close classifies each transaction as it posts, so the burn figure is ready on the day the month closes and contains no uncleared timing items.

    Debit & Co. runs this approach as the Continuous Close Method™. Bank accounts reconcile weekly, prepaid schedules roll forward before each close, and customer prepayments move through deferred revenue on a set schedule. Kevin Cahill reviews the runway bridge in every close packet before it ships.

    The bridge from bank burn to run-rate burn takes minutes when the ledger is clean. It takes days when it is not, which is why the corrected number usually arrives after the decision it should have informed.

    Frequently asked questions

    What are the most common burn rate mistakes startups make?

    The most common mistakes are reading burn from one month of bank movement, counting annual prepayments as one-month costs, counting upfront customer payments as income, and quoting gross burn as net. In the worked example, those errors move runway from 15.6 to 17.3 months.

    Should burn come from bank balance changes or from closed books?

    Use closed books as the source and the bank balance as a cross-check. The bank records when cash moved, while a reconciled ledger classifies payroll timing, card balances, financing inflows, and transfers before the division happens.

    How do one-time items and annual prepayments distort burn?

    They place cash movement in one month that belongs to twelve or to none. A $48,600 annual premium is $4,050/mo, and a $96,000 upfront customer payment is $8,000/mo. In September 2026, the example company’s bank burn of $112,550 became $124,800 after adjustment.

    What does your burn rate really tell investors about your startup?

    Burn shows how much time the next milestone has and whether management can reconcile its own numbers. A 1.7-month gap between bank runway and normalized runway can decide whether a milestone lands before or after a raise.

    How often should you recalculate burn and runway?

    Recalculate monthly after the close, using the trailing three-month average, and again after any hire, annual prepayment, debt draw, or raise. A weekly bank check is useful as an unreconciled warning, not as the reported figure.

    Sources: Internal Revenue Service, Publication 538, Accounting Periods and Methods. Worked example is illustrative.

  • Cash Flow vs. Revenue: Why Your P&L and Your Bank Balance Disagree

    Cash Flow vs. Revenue: Why Your P&L and Your Bank Balance Disagree

    The short answer: On cash flow vs revenue, revenue measures what a company has earned, while cash flow measures money that actually moved through the bank. In the worked example below, a software company books $106,300 of September profit while its bank balance falls $301,250.

    • Revenue follows performance under ASC 606; cash follows invoices, payment terms, and collections.
    • Receivables push revenue ahead of cash; deferred revenue pulls cash ahead of revenue.
    • A $144,000 annual contract paid upfront adds $144,000 of cash in month one but only $12,000 of revenue.
    • Watch reconciled cash and collections weekly; read revenue and margin at the monthly close.

    Last updated October 2026.

    Founders frequently confront two figures that refuse to reconcile. The income statement reports a profitable month, while the bank portal shows less money than the month before. Both figures can be accurate simultaneously.

    This guide defines each measure, explains the accounting rules that separate them, and analyzes a month in which profit and cash move in opposite directions. It concludes with the short list of indicators worth monitoring every week.

    A single US one-dollar bill standing on a reflective white surface, its mirror image below it, illustrating revenue and cash as two views of the same money
    Photo by NeONBRAND via Unsplash, Wikimedia Commons, CC0.

    Cash flow vs revenue: what is the difference?

    Revenue is the value a company has earned by delivering goods or services in a period. Cash flow is the net change in money held, regardless of when the underlying work happened.

    The two diverge because they operate on different clocks. Revenue begins when the company performs its obligations. Cash begins when the customer pays, and payment can arrive months before or after that performance.

    Tax rules show the same split. IRS Publication 538 explains that under the cash method, a business reports income “in the tax year you receive it.” Under the accrual method, it reports income “in the tax year you earn it, regardless of when payment is received.”

    Financial statements prepared under GAAP use the earned view for revenue. The cash flow statement then reconciles that view back to the bank.

    DimensionRevenueCash flow
    What it measuresValue earned by delivering goods or servicesNet money received and paid out
    Where it appearsIncome statement (P&L)Cash flow statement and the bank balance
    TriggerPerformance under the contractPayment clearing the bank
    Governing ruleASC 606 under GAAPActual receipts and disbursements
    Main reasons it leads or lagsReceivables, contract terms, multi-year dealsPayment terms, prepayments, capital spending, financing
    Best review cadenceMonthly, after the closeWeekly, from a reconciled balance

    Can revenue grow while cash shrinks?

    Yes. Revenue can rise every month while cash falls, because growth often means more unpaid invoices, more upfront spending, and longer customer payment cycles.

    Four mechanisms generate most of the difference. Customers on net-60 terms pay two months after the revenue posts. Payroll and vendor obligations leave the bank on schedule, independent of collections. Purchases of equipment or capitalized software consume cash without touching revenue. Prepaid annual tools pull a full year of spending into one month.

    Rapid growth amplifies each mechanism. A company that doubles its billings on net-60 terms also roughly doubles the receivables it must finance from its own balance sheet. Our guide to accounts receivable for startups shows how payment terms tie up runway.

    How does revenue recognition under ASC 606 create the gap?

    ASC 606 ties revenue to the delivery of goods or services, not to the invoice date or the payment date. That rule is the source of most timing differences between the P&L and the bank.

    The standard’s core principle, in FASB’s Accounting Standards Update 2014-09, is that an entity “recognizes revenue to depict the transfer of promised goods or services to customers.” The standard applies that principle through a five-step model, from identifying the contract to recognizing revenue as each obligation is satisfied.

    Payment is not among the recognition triggers. A company that finishes an implementation project in September recognizes that revenue in September, even if the customer pays in November. Errors in that judgment surface quickly in a transaction, as our analysis of revenue recognition in SaaS diligence explains.

    How does deferred revenue make cash arrive before revenue?

    Deferred revenue is cash, or an unconditional right to cash, received before the company delivers the service. It sits on the balance sheet as a liability and becomes revenue only as the work is performed.

    ASC 606 calls this a contract liability: an entity’s “obligation to transfer goods or services to a customer for which the entity has received consideration.” The update requires presenting it “when the payment is made or the payment is due (whichever is earlier).”

    Consider a $144,000 annual subscription paid upfront, with service delivered evenly across 12 months:

    • Month 1: cash rises by $144,000, revenue is $12,000, and deferred revenue is $132,000.
    • Month 3: cumulative revenue reaches $36,000, and deferred revenue falls to $108,000.
    • Month 12: cumulative revenue reaches $144,000, and deferred revenue reaches zero.

    Upfront billing therefore inflates cash early in the contract and contributes progressively less later. A company that spends its prepaid cash as if it were profit can run short in months 9 through 12.

    What does a month look like when profit and cash disagree?

    The illustrative example below follows a B2B software company with about $9.7M in annual revenue, closing September 2026 in QuickBooks Online. The P&L shows revenue of $812,400 and operating profit of $106,300.

    The bank statement presents a different picture. Customers on net-60 terms left receivables $268,900 higher at month-end. Deferred revenue fell $74,300, because more prepaid revenue was earned than new prepayments arrived.

    September 2026 lineP&L viewAdjustment to reach cashCash view
    Revenue vs. collections$812,400($268,900) receivables up; ($74,300) deferred revenue down$469,200
    Operating expenses vs. cash paid($706,100)($25,750) bills paid down and annual software prepaid($731,850)
    Capitalized software and equipmentNot expensed when paid($38,600) spent($38,600)
    Result$106,300 profit($407,550) gap($301,250) cash change

    What does the worked example change for a founder?

    The P&L suggests a self-funding company, while the bank shows one consuming cash. Each figure below comes from the table above.

    1. Collections rate. $812,400 − $268,900 − $74,300 = $469,200 collected, or 57.8% of revenue.
    2. Total gap. $106,300 − ($301,250) = $407,550 between profit and the change in cash.
    3. Runway. Cash falls from $3,450,000 to $3,148,750. At September’s pace, $3,148,750 ÷ $301,250 covers about 10.5 months.

    A founder reading only the P&L would see no runway constraint at all. The cash view shows a funding decision roughly 10 months out, and the receivables line shows where to act first.

    The statement-level mechanics are covered in our guide on how to read a startup cash flow statement.

    Which number should a founder watch week to week?

    Monitor cash weekly and revenue monthly. Cash can change materially within days, while revenue and margin become reliable only after the month is closed and reviewed.

    A practical weekly view fits on one page:

    • Bank balance reconciled to the statement, not the figure on the dashboard.
    • Collections received against the week’s forecast.
    • Receivables older than 60 days, by customer.
    • Committed payroll and vendor payments due in the next 14 days.

    Those four lines feed a rolling forecast. Our 13-week cash flow forecast guide shows how to build one, and our explainer on burn rate and runway covers the monthly companion metrics.

    How does a continuous close keep both numbers trustworthy?

    A continuous close reconciles cash, receivables, and deferred revenue as transactions post, so the weekly cash view and the monthly P&L draw on the same verified ledger.

    Debit & Co. runs this approach as the Continuous Close Method™. Bank accounts reconcile weekly, invoices and payments match as they arrive, and deferred revenue schedules roll forward before each close. Aaron Ressel reviews the revenue-to-cash bridge in every close packet before it ships.

    The result is one reconciled answer to two separate questions. Revenue indicates whether the business model works, and cash indicates how long the company can continue proving it.

    Frequently asked questions

    What is the difference between cash flow and revenue?

    Revenue is the value a company earns by delivering goods or services in a period, recognized under ASC 606. Cash flow is the net money that actually entered and left the bank. Timing differences from receivables, prepayments, and capital spending keep the two apart.

    Can revenue grow while cash shrinks?

    Yes. Growth on net-60 terms adds unpaid receivables, and payroll, vendor bills, and capital purchases leave the bank on schedule. In the worked example, a company earned $106,300 of operating profit in September 2026 while its cash fell $301,250.

    How does revenue recognition under ASC 606 create the gap?

    ASC 606 recognizes revenue as goods or services transfer to the customer, not when the invoice is paid. Work finished in September is September revenue even if the customer pays in November, so the P&L can run months ahead of the bank.

    How does deferred revenue make cash arrive before revenue?

    When a customer pays upfront, the cash lands immediately but the revenue is earned over the service period. A $144,000 annual contract paid in month one adds $144,000 of cash, $12,000 of revenue, and $132,000 of deferred revenue.

    Which number should a founder watch week to week?

    Cash. A reconciled bank balance, collections against forecast, receivables older than 60 days, and payments due in the next 14 days belong in the weekly view. Revenue and margin are best read monthly, after the close.

    Sources: Financial Accounting Standards Board, Accounting Standards Update 2014-09, Revenue from Contracts with Customers (Topic 606); Internal Revenue Service, Publication 538, Accounting Periods and Methods. Worked example is illustrative.

  • You Can’t Forecast Cash From Messy Books: Fix the Close Before the Model

    You Can’t Forecast Cash From Messy Books: Fix the Close Before the Model

    The short answer: A cash forecast is only as reliable as the books it starts from. In the worked example below, three bookkeeping errors overstated a company’s 13-week ending cash by $299,050, or 32.5%, and hid a breach of its $750,000 cash floor until week 10.

    • Fix the opening balance first: the bank reconciliation, then accounts payable, then the receivables aging.
    • A weekly forecast needs a cash balance reconciled to the bank within the last 7 days.
    • A close that finishes on calendar day 20 leaves the forecast running on data 34.5 days old, on average.
    • Cleanup and forecasting can run in parallel, but the forecast should not drive decisions until the opening balance ties.

    Last updated October 2026.

    Most forecast failures are diagnosed as modeling problems. The driver logic gets rebuilt, collection assumptions get tightened, and the spreadsheet grows another tab. The forecast still misses, because the inputs underneath it were never right.

    This guide traces how bookkeeping quality flows into a cash forecast, which errors do the most damage first, and how current the ledger must be for a weekly view. It closes with a sequencing answer for operators deciding between a cleanup and a model.

    A desk with a calculator, an open notebook of handwritten figures, and a laptop, set up for reconciling the books before a cash forecast
    Photo via Unsplash, Wikimedia Commons, CC0.

    How does bookkeeping quality affect a cash forecast?

    Bookkeeping quality sets three of the four inputs in a cash forecast: the opening balance, the expected receipts, and the committed disbursements. Only the growth assumptions come from management rather than the ledger.

    The arithmetic is simple. Ending cash equals opening cash plus receipts minus disbursements. A model can apply sophisticated logic to each term, yet every term inherits the ledger’s errors at full value.

    The IRS frames record-keeping in the same functional terms. Its record-keeping guidance states that “Everyone in business must keep records.” The same page lists two uses that matter here: “Monitor the progress of your business” and “Prepare your financial statements.” A forecast is one more use of the same records, and a demanding one.

    The errors also compound in time. A misstated opening balance shifts every one of the 13 weeks, while a missing bill distorts the weeks around its due date.

    Which bookkeeping problems break a cash forecast first?

    Unreconciled cash breaks a forecast first, because it moves the starting point of every week. Unrecorded payables come second, and a stale receivables aging comes third.

    Bookkeeping problemForecast line it distortsDirection of the errorTypical first symptom
    Unreconciled bank and card accounts, including duplicate deposits from the bank feedOpening balanceOverstates cash in every weekBook cash in QuickBooks Online disagrees with the bank portal
    Vendor bills sitting in an inbox, not entered in Bill.com or accounts payableDisbursementsUnderstates outflows in the weeks the bills fall duePayment runs larger than the forecast predicted
    Uncollectible or already-paid invoices left open in the agingReceiptsOverstates inflowsCollections lag the forecast for 3 or more weeks
    Missing accruals for payroll, taxes, and annual contractsDisbursementsUnderstates lumpy outflowsA quarterly or annual payment surprises the team
    Miscategorized transactionsDriver assumptionsDistorts run rates the model extrapolatesExpense lines swing month to month without a business reason

    The ranking follows reach. An opening-balance error touches all 13 weeks. A payables gap touches the weeks the bills come due, and a receivables error affects the weeks the cash was expected. Categorization errors matter most for longer horizons, where run rates drive the projection.

    How current do the books need to be to forecast weekly?

    A weekly cash forecast needs an opening balance reconciled to the bank within the past 7 days, plus payables entered as bills arrive. Monthly reconciliation alone cannot support a weekly view.

    The gap shows up in the age of the last verified balance. Assume a 30-day month and a forecast refreshed daily. If the close finishes on calendar day c, the last reconciled balance is, on average, 14.5 + c days old across the month.

    • A close finishing on calendar day 20 leaves the forecast starting from data 34.5 days old, on average.
    • A close finishing on calendar day 7 cuts the average age to 21.5 days.
    • Reconciling cash every Monday cuts it to about 3 days.

    The third case explains why fast monthly closes still leave weekly forecasts exposed. Our guide to reconciliation frequency covers the cadence by account type.

    What does a forecast built on messy books look like?

    The worked example below follows an illustrative $22M B2B services company building a 13-week forecast in October 2026. The books in QuickBooks Online report opening cash of $1,184,300, and the board has set a $750,000 minimum cash floor.

    A reconciliation pass found three errors. Customer payments of $96,400 had been recorded twice, once from the bank feed and once against the invoices. Vendor bills of $143,750 due within the 13 weeks were never entered. The aging carried $58,900 of invoices older than 120 days that the company did not expect to collect.

    13-week lineForecast on the books as keptCorrectionForecast on reconciled books
    Opening cash$1,184,300($96,400) duplicate deposits$1,087,900
    Receipts$2,610,000($58,900) uncollectible invoices$2,551,100
    Disbursements($2,874,500)($143,750) unrecorded bills($3,018,250)
    Ending cash, week 13$919,800($299,050)$620,750

    What does the worked example change for an operator?

    The reconciled forecast reverses the decision. On the books as kept, the company finishes the quarter $169,800 above its floor; on reconciled books, it finishes $129,250 below it.

    1. Size of the error. $96,400 + $58,900 + $143,750 = $299,050, which is 32.5% of the $919,800 the original model projected.
    2. Weekly net outflow. ($1,087,900 − $620,750) ÷ 13 = $35,935 a week, against $20,346 a week in the original model.
    3. Breach timing. ($1,087,900 − $750,000) ÷ $35,935 = 9.4 weeks, so the floor breaks during week 10.

    None of the three errors required a better model to find. Each surfaced in a standard reconciliation of cash, payables, and receivables. A team that learns of the breach in week 1 has nine weeks to draw a line of credit, accelerate collections, or defer spending.

    The forecast mechanics themselves are covered in our 13-week cash flow forecast guide.

    What is a continuous close, and how does it change cash visibility?

    A continuous close reconciles accounts as transactions post through the month, so month-end becomes a review step. For forecasting, it means the opening balance is verified every week rather than once a month.

    Debit & Co. runs this approach as the Continuous Close Method™. Bank and card accounts reconcile weekly, bills enter accounts payable as they arrive, and the receivables aging is reviewed before each forecast refresh. Aaron Ressel reviews every balance sheet reconciliation before the close packet ships.

    The practical effect is a shorter blind spot. The forecast starts each Monday from cash that ties to the bank, and the monthly close confirms work already done. Our five-day close calendar shows how the month-end portion compresses once reconciliation runs weekly.

    Should you clean up the books or build the forecast first?

    Start the cleanup first, and build the forecast alongside it, but do not let the forecast drive decisions until the opening balance ties to the bank. A model can be drafted in days; trust in its outputs depends on the ledger.

    A workable sequence for a company several months behind runs in four steps:

    1. Reconcile every bank and card account through the latest statement. This fixes the term that affects all 13 weeks.
    2. Enter every open vendor bill and confirm due dates, so the disbursement schedule is complete.
    3. Review the receivables aging, write off or reserve uncollectible balances, and apply unmatched payments.
    4. Build the forecast structure in parallel, then switch it to decision use once steps 1 through 3 hold for two consecutive weeks.

    For books more than a quarter behind, the work becomes a catch-up project before the recurring close; our catch-up bookkeeping guide sets out the order. Once the forecast is live, measuring its error each week shows whether the ledger stays clean, as our guide to cash flow forecast accuracy explains.

    The need is common. In the Federal Reserve Banks’ 2026 Report on Employer Firms, firms reported their most common reasons for seeking financing. Those reasons “were to meet operating expenses (56%) or to pursue an expansion or new opportunity (46%).” A financing request built on an unreconciled forecast asks a lender to underwrite the ledger’s errors.

    Frequently asked questions

    How does bookkeeping quality affect cash flow forecasting?

    The books supply the opening balance, expected receipts, and committed disbursements, so every bookkeeping error passes into the forecast at full value. In the worked example, three errors overstated 13-week ending cash by $299,050 and hid a breach of the company’s cash floor until week 10.

    Which bookkeeping problems break a cash forecast first?

    Unreconciled bank and card accounts break it first, because the opening balance shifts every week of the forecast. Unrecorded vendor bills come second, and a receivables aging that still carries uncollectible or already-paid invoices comes third.

    How current do your books need to be to forecast weekly?

    Cash should be reconciled to the bank within the past 7 days, with payables entered as bills arrive. A monthly close finishing on calendar day 20 leaves the forecast starting from data 34.5 days old on average, while weekly reconciliation cuts that to about 3 days.

    What is a continuous close and how does it change cash visibility?

    A continuous close reconciles accounts as transactions post through the month instead of waiting for month-end. The forecast then starts each week from cash that ties to the bank, and the monthly close becomes a review of work already completed.

    Should you clean up the books or build the forecast first?

    Start the cleanup first and build the forecast structure in parallel. Reconcile cash, enter open bills, and correct the receivables aging, then use the forecast for decisions once the opening balance has tied to the bank for two consecutive weeks.

    Sources: Internal Revenue Service, Why should I keep records?; Federal Reserve Banks, 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey. Worked example is illustrative.

  • How to Read a Startup Cash Flow Statement: Operating, Investing, and Financing, Explained

    How to Read a Startup Cash Flow Statement: Operating, Investing, and Financing, Explained

    The short answer: To read a startup cash flow statement, take the three sections in order: operating, investing, then financing. Their totals add up to the net change in cash for the period. In the worked example below, a seed-stage company used $1,046,900 in operations during one quarter, yet its cash balance rose $1,359,400 because a $4,000,000 round closed.

    • Operating activities show whether the product burns or produces cash. For most startups this is the line that sets runway.
    • Investing activities include cash moved into Treasury bills, which is parked, not spent.
    • Financing activities dominate the quarter a round closes, so a rising balance can hide a heavier burn.
    • A cash flow statement reports what already happened; a forecast estimates the next 13 weeks to 18 months.

    Last updated October 2026.

    Founders usually read the income statement first and the bank balance second. The cash flow statement sits between the two and explains why they disagree. It is also the report investors check first after a raise, because it shows how fast the new money is leaving.

    This guide walks through each section line by line, explains the net change in cash, and builds a full quarterly statement for an illustrative seed-stage company. It closes with the difference between the statement and a forecast.

    A founder writing notes beside a laptop while reviewing a startup cash flow statement
    Photo by JESHOOTS.COM via Unsplash, Wikimedia Commons, CC0.

    What are the three sections of a startup cash flow statement?

    A startup cash flow statement has three sections: operating, investing, and financing activities. Each one answers a different question about where cash came from and where it went.

    SectionTypical startup linesUsual sign at seed stageQuestion it answers
    Operating activitiesNet loss, stock-based compensation, receivables, deferred revenue, payablesNegativeHow much does running the product cost in cash?
    Investing activitiesLaptops and servers, purchases or maturities of Treasury billsNegative, often smallHow much cash went into long-lived assets or investments?
    Financing activitiesPreferred stock proceeds, issuance costs, option exercises, loan drawsPositive in a raise quarter, near zero otherwiseWho funded the gap?

    The order matters when reading. Operating cash shows whether the business model works yet. Investing and financing explain how the company paid for the shortfall.

    How do you read the operating section line by line?

    Read the operating section from net loss down, treating every line below it as a correction from accrual accounting back to cash. Most startup statements use this indirect method.

    The corrections fall into two groups. Noncash expenses come first. Stock-based compensation under ASC 718 and depreciation reduce net income without moving any cash, so they are added back.

    Working capital follows, and its sign convention trips up most first-time readers:

    • An increase in an asset, such as accounts receivable or prepaid software, consumed cash and appears as a negative.
    • An increase in a liability, such as accounts payable or deferred revenue, supplied cash and appears as a positive.
    • Decreases reverse both signs.

    Deferred revenue deserves a second look at any SaaS company. Annual prepayments arrive as cash long before they are earned under ASC 606, so a strong billing quarter can make operating cash look better than the underlying burn. A deeper diagnostic, including cash conversion ratios, appears in our guide to analyzing a cash flow statement.

    What belongs in investing activities at a startup?

    Investing activities at a startup usually hold equipment purchases and any cash moved into short-term investments. Both reduce the bank balance, though only one of them is spending.

    The SEC’s beginner’s guide says investing activities “generally include purchases or sales of long-term assets, such as property, plant and equipment, as well as investment securities.” For a software company, equipment is typically modest: laptops, monitors, and occasionally servers.

    Treasury bills are the line that confuses board members. After a raise, many companies place part of the round in bills the company classifies as short-term investments. The purchase shows as an investing outflow. The cash still belongs to the company, and it returns as an investing inflow at maturity.

    Reading investing activities therefore means separating the two. Capital spending belongs in the burn calculation. Treasury purchases belong in the liquidity total.

    Why does the financing section dominate right after a raise?

    Financing dominates after a raise because the round arrives as one large inflow inside a single period. In a seed or Series A quarter, it often exceeds the operating outflow several times over.

    The SEC guide describes the section simply: “Typical sources of cash flow include cash raised by selling stocks and bonds or borrowing from banks.” For a venture-backed company, that means preferred stock proceeds, net of legal and other issuance costs, plus small option exercises.

    The effect on reading is direct. A quarter with $3,942,800 of financing inflow and $1,046,900 of operating outflow shows cash rising sharply. Nothing about the burn improved. The fair comparison is operating cash against the prior quarter’s operating cash, with financing set aside.

    SAFEs add one more wrinkle. The cash arrives when each SAFE is signed and funded. When those SAFEs later convert into preferred stock, no cash moves, so the conversion adds nothing to that quarter’s financing total.

    What is the net change in cash, and how does it tie out?

    The net change in cash is the sum of the three section totals. Added to the opening balance, it must equal the closing balance on the balance sheet, to the dollar.

    In the SEC’s words, “The bottom line of the cash flow statement shows the net increase or decrease in cash for the period.” That bottom line is also the fastest integrity check available to a founder.

    Restricted cash is part of the total. FASB’s ASU 2016-18 requires the statement to “explain the change during the period in the total of cash, cash equivalents, and amounts generally described as restricted cash or restricted cash equivalents.” A letter-of-credit deposit backing an office lease is a common startup example.

    For private companies, the update took effect for fiscal years beginning after December 15, 2018. When the reconciled total misses the bank and the balance sheet, the break usually sits in an unreconciled account or a cutoff error. Our guide to building startup financial statements covers how the three reports tie together.

    What does an example startup cash flow statement look like?

    The example below is an illustrative seed-stage SaaS company for the quarter ended September 30, 2026. It closed a $4,000,000 priced seed round in August and placed $1,500,000 in 6-month Treasury bills.

    Line, quarter ended September 30, 2026Amount
    Net loss($1,146,300)
    Stock-based compensation$38,400
    Depreciation and amortization$21,700
    Increase in accounts receivable($64,900)
    Increase in prepaid expenses($47,200)
    Increase in accounts payable and accrued expenses$58,600
    Increase in deferred revenue$92,800
    Net cash used in operating activities($1,046,900)
    Purchases of equipment($36,500)
    Purchases of Treasury bills($1,500,000)
    Net cash used in investing activities($1,536,500)
    Proceeds from seed preferred stock, net of $61,400 issuance costs$3,938,600
    Proceeds from stock option exercises$4,200
    Net cash provided by financing activities$3,942,800
    Net change in cash, cash equivalents, and restricted cash$1,359,400
    Beginning balance, including $50,000 restricted$1,212,600
    Ending balance, including $50,000 restricted$2,572,000

    The ending balance ties: $1,212,600 + $1,359,400 = $2,572,000.

    What does the worked example tell a founder?

    It shows a quarter in which cash rose $1,359,400 while the company burned more than $1,000,000. Four calculations turn the statement into decisions.

    1. Operating burn. $1,046,900 ÷ 3 months = $348,967 a month.
    2. Net burn with equipment. ($1,046,900 + $36,500) ÷ 3 = $361,133 a month.
    3. Liquidity. $2,522,000 of unrestricted cash plus $1,500,000 of Treasury bills = $4,022,000.
    4. Runway. $4,022,000 ÷ $361,133 = 11.1 months at the current burn.

    Financing covered operations 3.8 times in this quarter ($3,942,800 ÷ $1,046,900). Operating cash ran $99,400 lighter than the net loss, and deferred revenue supplied $92,800 of that gap. Annual prepayments, not efficiency, explain most of the difference.

    Kevin Cahill reviews this reconciliation with founders before each board meeting. The runway mechanics are covered in our guide to burn rate and runway.

    How is the cash flow statement different from a cash flow forecast?

    The cash flow statement is historical and follows GAAP; a cash flow forecast is forward-looking and follows management’s assumptions. A company needs both, for different decisions.

    FeatureCash flow statementCash flow forecast
    Time directionA closed month, quarter, or yearThe next 13 weeks to 18 months
    RulesGAAP, ASC 230Management assumptions
    SourceThe closed ledger in QuickBooks Online or NetSuitePipeline, hiring plan, vendor terms
    Primary readerBoard, investors, auditorsFounder and finance lead
    Decision it supportsWas the plan executed?When to raise, hire, or cut

    The statement also calibrates the forecast. Each closed month replaces a forecast month with actuals, and the variance shows which assumptions drifted. Teams on the Continuous Close Method™ produce that statement within days of month-end, so the comparison stays current.

    The forecast side is covered in what a cash flow forecast is and the 13-week cash flow forecast. Startups that want both maintained can use our outsourced CFO services.

    Sources: SEC, Beginners’ Guide to Financial Statements; FASB, Accounting Standards Update 2016-18, Restricted Cash.

    Frequently asked questions

    What are the three sections of a cash flow statement?

    Operating, investing, and financing activities. Operating covers cash from running the business, investing covers equipment and investment purchases or sales, and financing covers equity raised, debt drawn, and debt repaid. At a seed-stage startup, operating is usually negative and financing is positive in the quarter a round closes.

    What is the net change in cash on a cash flow statement?

    It is the sum of the operating, investing, and financing totals for the period. Added to the opening balance, it must equal the closing balance of cash, cash equivalents, and restricted cash. In the worked example, $1,212,600 plus $1,359,400 equals $2,572,000.

    Why does the financing section dominate right after a raise?

    The round lands as one large inflow in a single period. In the example, $3,942,800 of financing covered $1,046,900 of operating outflow 3.8 times, so cash rose even though the burn did not improve. Compare operating cash quarter over quarter with financing set aside.

    What does an example startup cash flow statement look like?

    It starts with net loss, adds back stock compensation and depreciation, then adjusts for receivables, prepaids, payables, and deferred revenue. Equipment and Treasury bill purchases follow under investing, then preferred stock proceeds net of issuance costs under financing. The total ties to the ending cash balance.

    How is the cash flow statement different from a cash flow forecast?

    The statement reports a closed period under GAAP and shows what already happened. The forecast projects the next 13 weeks to 18 months from management assumptions and supports raise, hiring, and spending decisions. Each closed month’s statement replaces a forecast month with actuals.

  • A Cash Flow Forecast for a Seed-Stage SaaS Company, Line by Line (Worked Example)

    A Cash Flow Forecast for a Seed-Stage SaaS Company, Line by Line (Worked Example)

    The short answer: A SaaS cash flow forecast starts from reconciled bank cash, then projects receipts and payments by month, line by line. In the worked example below, a seed-stage SaaS company opens January with $2,159,450, burns $491,049 over six months, and finishes June with $1,668,401, about 20 months of runway at its average net burn of $81,842 a month.

    • Collections from annual prepaid contracts arrive in lumps, so a single month’s burn can understate the true run rate by more than half.
    • Deferred revenue is the gap between cash in the bank and revenue on the income statement; the forecast must follow cash.
    • Employer payroll taxes are front-loaded each January, when federal and state unemployment wage bases reset.
    • Runway should be measured on a trailing multi-month average burn, never on the best month.

    Last updated October 2026.

    A SaaS cash flow forecast is a month-by-month projection of the cash a subscription company will collect and spend, starting from the balance actually in the bank. At seed stage it answers one question: how many months the company can operate before it needs new capital.

    Generic templates miss the lines that move cash in a subscription business. Annual prepayments, card processing, net-30 invoices, and January payroll taxes all shift cash between months. This guide builds a six-month forecast for a modelled seed-stage SaaS company, one line at a time, with the arithmetic shown.

    Laptop, notebook, and sticky notes on a desk, representing a seed-stage SaaS company planning a monthly cash flow forecast
    Photo by Pixel.la Free Stock Photos, Wikimedia Commons, CC0.

    What does a seed-stage SaaS cash flow forecast need to show?

    It needs to show opening cash, each receipt and payment line by month, monthly net burn, and closing cash. Runway follows directly from those four rows.

    The example company is modelled, though every figure is computed exactly. It sells B2B software, has 11 employees, and closed a seed round last year. Customers buy either a monthly plan paid by card or an annual plan invoiced upfront on net-30 terms.

    The horizon here is January through June, in monthly buckets. A seed company deciding when to raise needs a 12–18-month view; a company managing a tight cash position needs weekly detail instead. Our guide to the 13-week cash flow forecast covers that weekly version. The broader method sits in how to build a cash flow forecast.

    How do you calculate the opening cash balance?

    Take the bank statement balance, add deposits in transit, and subtract payments that have left the books but not yet cleared the bank. The result is reconciled cash, the only defensible starting point.

    On December 31, the company’s bank statement shows $2,184,600. A customer payment of $11,250 was deposited but had not posted. Two vendor payments totalling $36,400 were released but had not cleared.

    The opening balance is therefore $2,184,600 + $11,250 − $36,400 = $2,159,450. Starting from the raw statement figure would overstate cash by $25,150. That error would carry into every later month.

    How do you forecast SaaS collections from monthly and annual plans?

    Forecast each billing type on its own line, because each converts to cash on a different schedule. Card-paid monthly plans arrive almost immediately; invoiced annual plans arrive weeks later, and in lumps.

    Monthly plans. Monthly recurring revenue is $38,500 in January and grows by $2,200 a month. Card processing costs are assumed at 3% of volume. January card receipts are $38,500 × 0.97 = $37,345, rising to $48,015 by June.

    Annual plans. Annual contracts are invoiced in full at signing. History shows 70% of each month’s invoices are paid the following month, and 30% the month after that. December was a heavy month, with $180,000 invoiced as customers spent remaining budgets.

    January’s annual collections are 70% of December plus 30% of November: $126,000 + $28,800 = $154,800. February drops to $91,800, and March to $66,600. Accounts receivable on December 31 was $208,800, which reconciles exactly to the cash those two months draw from it.

    MonthAnnual invoices billedAnnual collectionsCard receipts (net)Total receipts
    January$54,000$154,800$37,345$192,145
    February$72,000$91,800$39,479$131,279
    March$120,000$66,600$41,613$108,213
    April$60,000$105,600$43,747$149,347
    May$84,000$78,000$45,881$123,881
    June$66,000$76,800$48,015$124,815

    Receipts swing from $108,213 to $192,145 while the business grows steadily. The swing is timing, not demand.

    Why does deferred revenue make cash and revenue diverge?

    Annual prepayments put cash in the bank before the service is delivered, so revenue trails cash. The forecast follows cash; the income statement follows delivery.

    Under ASC 606, a 12-month subscription invoiced upfront is generally recognized as revenue ratably over the service period. Cash received before the service is delivered sits on the balance sheet as a contract liability, usually called deferred revenue.

    December’s $180,000 of annual contracts adds $15,000 of revenue in each of the next 12 months. Most of that cash arrives in January alone. A founder who forecasts cash from the income statement will mistime $126,000 of January receipts.

    The reverse error is equally costly. Booking a large annual deal can make the income statement look flat while the bank balance jumps. Diligence teams test exactly this reconciliation, as covered in how revenue recognition breaks SaaS diligence.

    How do you forecast payroll, employer taxes, and benefits?

    Forecast gross wages, then add employer taxes and benefits as separate lines. Unemployment taxes belong in the months they are incurred, which concentrates them early in the year.

    Gross payroll for the 11 employees is $132,000 a month. The employer pays 6.2% Social Security tax and 1.45% Medicare tax, a combined 7.65% according to IRS Topic 751. That adds $10,098 a month, assuming no salary crosses the Social Security wage base. Employer-paid benefits run $850 per employee, or $9,350 a month.

    Unemployment taxes behave differently. IRS Topic 759 sets the federal (FUTA) rate at 6.0% on the first $7,000 of each employee’s wages. An employer entitled to the full 5.4% state credit pays 0.6%, or $42 per employee.

    State wage bases vary. The example assumes a 2.7% state rate on a $7,000 base. Every employee here earns $12,000 a month, so both bases are exhausted in January:

    • Federal: 11 × $7,000 × 0.6% = $462.
    • State: 11 × $7,000 × 2.7% = $2,079.
    • January payroll cash: $132,000 + $10,098 + $9,350 + $2,541 = $153,989.
    • February through June: $151,448 a month.

    The amounts are small here. For a 40-person company with higher state rates, the January bump can reach tens of thousands of dollars. It recurs every year.

    Which non-payroll lines belong in the forecast?

    Every recurring vendor payment, plus each annual or quarterly bill in the month it is paid. Annual bills are the lines most often missed.

    • Cloud hosting: $14,200 in January, rising $600 a month with usage, to $17,200 by June.
    • Software subscriptions: $6,350 a month, plus annual renewals of $28,800 in January and $11,400 in April.
    • Rent and coworking: $7,900 a month.
    • Contractors and paid marketing: $18,500 a month.
    • Accounting and legal: $9,500 a month.
    • Insurance: a $21,600 annual premium for directors and officers and cyber coverage, paid in March.

    The recurring lines total $42,250 a month before hosting. The three annual items add $61,800 across the half-year, concentrated in January, March, and April.

    What does the full six-month forecast look like?

    Combine receipts and payments by month, net them, and roll each closing balance into the next month’s opening balance. The table below is the complete model.

    MonthOpening cashReceiptsPayrollHostingOther paymentsNet burnClosing cash
    January$2,159,450$192,145$153,989$14,200$71,050−$47,094$2,112,356
    February$2,112,356$131,279$151,448$14,800$42,250−$77,219$2,035,137
    March$2,035,137$108,213$151,448$15,400$63,850−$122,485$1,912,652
    April$1,912,652$149,347$151,448$16,000$53,650−$71,751$1,840,901
    May$1,840,901$123,881$151,448$16,600$42,250−$86,417$1,754,484
    June$1,754,484$124,815$151,448$17,200$42,250−$86,083$1,668,401
    Total$829,680$911,229$94,200$315,300−$491,049

    Check the model before trusting it. Opening cash less total net burn must equal June’s closing cash: $2,159,450 − $491,049 = $1,668,401. It does.

    The pattern matters more than any single cell. January looks like the cheapest month, at $47,094 of net burn. March is the costliest, at $122,485, because the insurance premium lands just as annual collections dip. The spread between them is 2.6 times.

    How do you turn the forecast into runway?

    Divide closing cash by average monthly net burn over several months. One month is too noisy to use on its own in a business with annual billing.

    Six-month net burn is $491,049, or $81,842 a month on average. June’s closing cash of $1,668,401 divided by $81,842 gives about 20.4 months of runway.

    Using January alone would mislead badly. January closing cash of $2,112,356 divided by January’s $47,094 burn suggests 44.9 months. That figure is more than twice the real answer, and it would push a fundraise back by more than a year. Our guide to burn rate and runway explains why net burn, not gross burn, drives this calculation.

    How should a seed-stage SaaS company stress-test the forecast?

    Change one assumption at a time and measure how far runway moves. The two assumptions that matter most at seed stage are hiring dates and collection timing.

    Hiring. Suppose two engineers join in April at $13,000 a month each. April payroll rises by $30,151: $26,000 of wages, $1,989 of employer FICA, $1,700 of benefits, and $462 of unemployment tax. May and June each rise by $29,689. June closing cash falls to $1,578,872.

    The run rate changes more than the balance. June net burn becomes $86,083 + $29,689 = $115,772. Runway on that run rate is $1,578,872 ÷ $115,772, or 13.6 months. Two hires cut almost seven months of runway.

    Collections. Suppose March’s $120,000 of annual invoices pays one month late. April receipts fall by $84,000, and the cash lands in May instead. June closing cash and runway do not change, yet April’s closing balance drops by $84,000 for a month. A company near a bank covenant floor would breach it.

    Both stresses belong in the board pack. Kevin Cahill reviews each forecast scenario against the latest close before it reaches a board. The forecast is only as reliable as the close it starts from, which is the premise of the Continuous Close Method™. The cash flow forecast accuracy guide shows how to score the model once actuals arrive.

    Frequently asked questions

    How do you calculate the opening balance for a cash flow forecast?

    Start with the bank statement balance, add deposits in transit, and subtract payments released but not yet cleared. In the worked example, $2,184,600 + $11,250 − $36,400 gives a reconciled opening balance of $2,159,450, which is $25,150 lower than the raw statement.

    How do you calculate a cash flow forecast for a startup?

    Begin with reconciled opening cash, project each receipt and payment line by month, and subtract payments from receipts to get net burn. Roll each closing balance into the next month. Runway equals closing cash divided by average net burn across several months, not a single month.

    How do you forecast payroll, benefits, and payroll-tax timing?

    Forecast gross wages, then add employer Social Security at 6.2% and Medicare at 1.45%, plus employer-paid benefits. Place federal and state unemployment taxes in the months wages first reach each wage base, which for most salaried staff is January.

    How should annual prepayments and deferred revenue appear in the forecast?

    Annual prepayments appear as receipts in the month the customer pays, not spread over the contract. Under ASC 606 the revenue is generally recognized ratably, so deferred revenue holds the difference. The forecast follows cash; the income statement follows delivery.

    How do you forecast collections when customers pay on net-30 terms?

    Use actual payment history rather than the invoice terms. If 70% of invoices are paid the following month and 30% the month after, apply those percentages to each month’s billings. Then confirm the projected collections reconcile to the opening accounts receivable balance.

  • How Accurate Is Your Cash Forecast? Measuring, Tracking, and Improving Forecast Accuracy

    How Accurate Is Your Cash Forecast? Measuring, Tracking, and Improving Forecast Accuracy

    The short answer: Cash flow forecast accuracy is measured by comparing each forecast line with the cash that actually cleared, then tracking the error over time. Four numbers do the work: closing-balance error, absolute error, percentage error on gross receipts and payments, and bias. In the worked example below, an 8-week collections forecast scores a comfortable 5.5% MAPE, yet a hidden bias would drain $92,625 from a $350,000 cushion over 13 weeks.

    • Measure accuracy on gross receipts, gross payments, and closing cash, never on net cash flow, where small misses produce percentage errors above 100%.
    • Bias, the average signed error, matters more than average size: a forecast that misses in one direction compounds into a cash shortfall.
    • Set the tolerance from the cash cushion above your minimum balance, not from a generic industry percentage.
    • Most drift traces back to timing, unreconciled opening balances, and annual bills missing from the model.

    Last updated October 2026.

    Cash flow forecast accuracy is the gap between the cash a model predicted and the cash the bank actually reported. Most startups never measure it. They rebuild the forecast each week, overwrite last week’s numbers, and lose the only evidence of how good the model is.

    A forecast that is never scored cannot improve. This guide sets out the accuracy metrics that work for cash, an acceptable variance for a startup, and a weekly routine that keeps the model honest. One worked example runs the math on eight real-shaped weeks.

    Laptop screen showing a financial chart and data table, representing cash flow forecast accuracy tracking
    Photo by Negative Space, Wikimedia Commons, CC0.

    How is cash forecast accuracy measured?

    Cash forecast accuracy is measured by recording the forecast error for each line and period, where error equals actual cash minus forecast cash. Those errors are then summarized into a few metrics.

    The first step is the one most teams skip. Save a locked copy of each forecast before the week starts. Without that snapshot, there is nothing to compare against once actuals arrive from QuickBooks Online or the bank feed.

    Rob Hyndman and George Athanasopoulos, in their widely used text Forecasting: Principles and Practice, describe absolute errors as “scale-dependent.” Such measures “cannot be used to make comparisons between series that involve different units.” Percentage errors fix that problem, which is why finance teams favor them for comparing lines of different size.

    Which metrics measure cash flow forecast accuracy?

    Use four metrics together: closing-balance error, mean absolute error, percentage error on gross flows, and bias. Each catches a failure the others miss.

    MetricFormulaWhat it catchesBlind spot
    Closing-balance errorActual closing cash − forecast closing cashThe number the covenant and payroll depend onOffsetting misses can cancel out
    Mean absolute error (MAE)Average of |actual − forecast|Typical miss size in dollarsCannot compare lines of different size
    Mean absolute percentage error (MAPE)Average of |error| ÷ actualRelative accuracy across receipts and paymentsBreaks when the actual is near zero
    BiasAverage of signed errorsSystematic optimism or pessimismSays nothing about miss size

    MAPE carries a trap for cash. Hyndman and Athanasopoulos warn that percentage errors risk “being infinite or undefined” when the actual is zero, “and having extreme values if any” actual “is close to zero.” Net weekly cash flow often sits near zero, so MAPE on that line is meaningless.

    Consider a week forecast at +$4,000 of net cash that lands at +$1,000. The $3,000 miss reads as a 300% error on net flow. Against $180,000 of gross receipts, the same miss is 1.7%. Score receipts and payments separately, then score closing cash in dollars.

    How do you calculate forecast accuracy? A worked example

    Compare eight weeks of locked forecasts with actual collections, then compute the four metrics. The example below is modelled, but the arithmetic is exact.

    Consider a Series A software company with $1,350,000 of cash and a $1,000,000 minimum-liquidity covenant, which leaves a $350,000 cushion. Its finance lead forecasts customer collections one week ahead, in thousands of dollars:

    WeekForecastActualError (A − F)Absolute % error
    1182176−63.41%
    2165171+63.51%
    3210188−2211.70%
    4148151+31.99%
    5196179−179.50%
    6172168−42.38%
    7205186−1910.22%
    8160162+21.23%
    Total1,4381,381−57MAPE 5.49%

    The arithmetic runs in three lines. MAE is 79 ÷ 8 = $9,875 a week. MAPE is 43.94% ÷ 8 = 5.49%. Bias is −57 ÷ 8 = −$7,125 a week, or 3.96% of forecast collections.

    A 5.49% MAPE looks acceptable. The bias does not. Five of eight weeks came in short, and all three large misses were over-forecasts. Each fell in a week when an enterprise invoice on net-45 terms was due and paid late.

    Projected across a 13-week horizon, the bias compounds: 13 × $7,125 = $92,625. That consumes 26.5% of the $350,000 cushion before anything else goes wrong.

    What is an acceptable forecast variance for a startup?

    An acceptable variance is one the cash cushion can absorb. No accounting standard sets a universal percentage, so the tolerance has to come from the company’s own balance sheet.

    Start with the cushion: current cash less the minimum balance a lender, payroll, or board policy requires. Divide it across the forecast horizon. A $350,000 cushion over 13 weeks allows roughly $26,923 of cumulative error per week before the floor is at risk.

    Then set line-level review triggers below that limit. One workable rule flags any line where the weekly miss exceeds 5% of the line or $10,000, whichever is larger. Near-term weeks should hold tighter than weeks 9–13, because invoices and bills are already known.

    Thin cushions raise the stakes. The Federal Reserve Banks’ 2026 Report on Employer Firms, drawn from the 2025 Small Business Credit Survey, found that “Sixty percent of firms applied for financing” in the prior 12 months. The most common reason was “to meet operating expenses (56%),” which is the borrowing an accurate forecast schedules early rather than in a scramble.

    Why do cash forecasts drift from reality?

    Cash forecasts drift for four recurring reasons, and most of them are timing, not volume. Classifying each variance by cause is what turns a miss into a fix.

    • Collection timing. Customers pay on their own schedule, not the invoice terms. A net-30 invoice that historically pays in 41 days belongs in week 6, not week 5.
    • Stale opening cash. A forecast that starts from an unreconciled balance carries the error into every later week.
    • Missing annual items. Insurance premiums, software renewals, and the Delaware franchise tax rarely sit in a weekly template.
    • Optimism. Sales-led collection estimates tend to run high, which shows up as negative bias.

    Each variance should be tagged as timing or permanent. A timing miss reverses in a later week; a permanent miss changes the closing balance for good. Our guide to variance analysis in the month-end close applies the same discipline to the income statement.

    How does close speed affect forecast accuracy?

    A faster close improves forecast accuracy because every forecast starts from the last verified balance. A slow close means the model runs on unreconciled data for weeks.

    Take a company that closes on calendar day 20. September is not reconciled until October 20, so the forecast runs nearly three weeks of October on unverified categories. Any miscoded receipt or missing bill rides along the whole time.

    Closing in five business days, about seven calendar days, cuts that blind period by roughly two weeks. Our five-day close calendar sets out the sequence. Under the Continuous Close Method™, bank and card reconciliations run as transactions post, so the forecast can start from verified cash every Monday.

    What weekly variance-review routine keeps a forecast honest?

    A 30-minute weekly review is enough for most startups. The routine compares last week’s locked forecast with actuals, explains the large misses, and feeds the causes back into the model.

    1. Monday: reconcile the bank balance and roll the 13-week cash flow forecast forward one week.
    2. Pull actual receipts and payments by line from the bank feed and accounts payable.
    3. Compute the error, percentage error, and running bias for each line.
    4. Explain every line over its trigger, and tag it as timing or permanent.
    5. Update the driver behind each permanent miss, such as days to collect for one customer.
    6. Lock a new snapshot before any cash moves, and log the four metrics in one running table.

    The running table is the asset. After 13 weeks, it shows which lines the model gets right and which it misses in the same direction every week. Kevin Cahill reviews that bias trend with founders each month, alongside the rolling cash flow forecast. The build itself is covered in our guide on how to build a cash flow forecast, and the weekly review is part of our outsourced CFO services.

    Sources: Hyndman and Athanasopoulos, Forecasting: Principles and Practice (3rd ed.), section 5.8, Evaluating point forecast accuracy; Federal Reserve Banks, 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey.

    Frequently asked questions

    How is cash forecast accuracy measured?

    Save a locked copy of each forecast, then compare every line with the cash that actually cleared. Error equals actual minus forecast. Summarize the errors with four metrics: closing-balance error in dollars, mean absolute error, mean absolute percentage error on gross receipts and payments, and bias, which is the average signed error.

    What is an acceptable forecast variance for a startup?

    An acceptable variance is one the cash cushion can absorb. Subtract the required minimum balance from current cash and spread that cushion across the forecast horizon. A $350,000 cushion over 13 weeks allows about $26,923 of cumulative error per week. Line-level review triggers should sit well below that limit.

    Why do cash forecasts drift from reality?

    Most drift comes from four causes: customers paying later than invoice terms, forecasts starting from an unreconciled opening balance, annual bills missing from a weekly template, and optimistic collection estimates. Tagging each variance as timing or permanent shows which drivers in the model need to change.

    How does close speed affect forecast accuracy?

    Every cash forecast starts from the last verified balance. A company that closes on day 20 runs its forecast on unreconciled data for weeks, so coding errors and missing bills flow into every later period. Closing in five business days cuts that blind period by roughly two weeks.

    What weekly variance-review routine keeps a forecast honest?

    Reconcile the bank balance, roll the forecast forward, and pull actuals by line. Compute each line’s error and running bias, explain any line over its review trigger, and tag it as timing or permanent. Update the driver behind each permanent miss, then lock a new snapshot before any cash moves.

  • Direct vs. Indirect Cash Flow Forecasting: Two Methods, Two Horizons, One Decision

    Direct vs. Indirect Cash Flow Forecasting: Two Methods, Two Horizons, One Decision

    The short answer: In direct vs. indirect cash flow forecasting, the direct method schedules actual receipts and payments for the next 13 weeks to 6 months. The indirect method starts from projected net income and covers months 4 through 36. In the worked quarter below, both methods land on the same −$22,000, yet only the direct view exposes a $103,000 covenant breach in November.

    • The direct method answers “will we have cash on a given date”; the indirect method answers “why does cash differ from profit.”
    • Both methods must reconcile to the same operating cash flow total, which makes the seam between them a free error check.
    • At $8.4M of annual revenue, every extra day of collections absorbs about $23,014 of cash, a driver the indirect model handles well.
    • Most companies with under 18 months of cash should run both: direct for the near term, indirect for the long range.

    Last updated October 2026.

    Two finance leads can forecast the same quarter and hand the board two different stories. One reports a modest $22,000 operating outflow. The other reports a month where cash falls $103,000 below the lender’s minimum. Both models can be arithmetically correct.

    The difference is method. This guide compares the two approaches and assigns each to its horizon. It then builds one modelled quarter both ways, so the gap between them is visible line by line.

    Laptop showing financial charts on a desk, representing a direct vs indirect cash flow forecast model
    Photo by rawpixel, Wikimedia Commons, CC0.

    What is the direct method of cash flow forecasting?

    The direct method projects each major class of cash receipt and cash payment on the date it will clear the bank. Opening cash plus receipts minus payments gives closing cash for every period.

    Its inputs are operational records. Collections come from the receivables aging and customer payment history. Payroll comes from the pay calendar. Vendor payments come from bills already entered in QuickBooks Online or Bill.com and their due dates.

    The accounting standard behind the cash flow statement describes the same logic. FASB Statement 95, now codified in ASC 230, encourages reporting “major classes of gross cash receipts and gross cash payments and their arithmetic sum” as the direct method. The Board noted that such detail “may be useful in estimating future operating cash flows,” which is the direct forecast’s premise.

    What is the indirect method, and how do you forecast cash flows from financial statements?

    The indirect method starts with projected net income and adjusts it for noncash expenses and changes in working capital. The result is operating cash flow for the period, without naming a single invoice.

    The build runs from a projected income statement and balance sheet. Add back depreciation, amortization, and stock-based compensation under ASC 718. Subtract increases in receivables and prepaid expenses. Add increases in payables, accruals, and deferred revenue recognized under ASC 606.

    Statement 95 states the cost plainly: the indirect method “does not disclose operating cash receipts and payments.” What it shows instead is the bridge from earnings to cash. Our guide to analyzing the cash flow statement reads that bridge on historical results; a forecast applies it to projected ones.

    Direct vs. indirect cash flow forecasting: how do the two methods compare?

    The direct method trades effort for timing precision, and the indirect method trades timing precision for reach. The table sets out where each one earns its place.

    DimensionDirect methodIndirect method
    Starting pointReconciled bank cashProjected net income
    Typical horizon13 weeks to 6 months12 to 36 months
    Period lengthWeekly or monthlyMonthly or quarterly
    Core inputsAR aging, pay calendar, open bills, debt scheduleIncome statement, DSO, DPO, deferred revenue, capex
    Question answeredDo we clear the minimum on a specific date?Why will cash differ from profit next year?
    Typical blind spotGuesswork once invoices are not yet issuedIntra-quarter troughs and lumpy payments
    Main usersController, treasury, lender reportingCFO, board, fundraising plan

    Neither column is the better method in the abstract. Each fails in a predictable place, and the failure points sit at opposite ends of the calendar.

    How do both methods forecast the same quarter?

    Built correctly, the two methods produce an identical quarterly operating cash figure. They diverge on the path between the opening and closing balances.

    Consider a modelled venture-backed software company with $8.4M of annual revenue, near breakeven, entering October 2026 with $1,140,000 of cash. Its term loan requires minimum liquidity of $1,000,000 at every month-end. Annual renewals are invoiced on November 15 with net-30 terms. Every figure is illustrative.

    The indirect bridge for the quarter, in thousands of dollars:

    Indirect bridge, Q4 2026$ thousands
    Projected net income (loss)(310.0)
    Depreciation and amortization42.0
    Stock-based compensation96.0
    Increase in accounts receivable(385.0)
    Increase in deferred revenue512.0
    Increase in payables and accruals61.0
    Increase in prepaid expenses(38.0)
    Net cash from operations(22.0)

    The arithmetic: −310 + 42 + 96 − 385 + 512 + 61 − 38 = −22. Closing cash is $1,140,000 − $22,000 = $1,118,000. The covenant appears safe with $118,000 of room.

    What does the direct view show that the indirect view hides?

    The direct view shows a November trough that breaches the covenant by $103,000. The quarterly bridge averages it away.

    Direct forecast ($ thousands)OctoberNovemberDecemberQuarter
    Opening cash1,140.01,111.0897.01,140.0
    Collections from customers712.0598.0917.02,227.0
    Payroll, taxes, and benefits(486.0)(489.0)(492.0)(1,467.0)
    Vendors and software(168.0)(214.0)(131.0)(513.0)
    Rent, insurance, and interest(87.0)(109.0)(73.0)(269.0)
    Net operating cash(29.0)(214.0)221.0(22.0)
    Closing cash1,111.0897.01,118.01,118.0

    Three things collide in November. Renewal invoices go out mid-month, so their cash lands in December. An annual insurance premium and a data-warehouse prepayment both fall due. Collections drop to $598,000 while payments peak at $812,000.

    November closes at $1,111,000 − $214,000 = $897,000, which is $103,000 under the $1,000,000 floor. Six weeks of warning is enough to move the prepayment, draw a revolver, or invoice renewals on November 1.

    Why do both methods have to reconcile?

    Both methods describe the same cash, so their operating totals must match. The direct quarter sums to $2,227,000 of collections less $2,249,000 of payments, or −$22,000, exactly the bridge total.

    The reporting standard builds in the same discipline. Under Statement 95, a company skipping the direct method “shall determine and report the same amount for net cash flow from operating activities indirectly” through the bridge. The net income reconciliation is required “regardless of whether the direct or indirect method” is used.

    For a forecast, that rule becomes a control. Set a tolerance, for example 2% of the quarter’s payments ($44,980 here), and investigate any seam gap above it. A large gap usually means a missed accrual, an unscheduled annual bill, or a collection assumption that no longer matches the aging.

    Which method fits short-term vs. long-term forecasting?

    Use the direct method for roughly the next 13 weeks to 6 months, and the indirect method beyond that. Precision is worth the labor only while the underlying transactions are known.

    Near-term cash is mostly committed. Invoices are issued, bills are entered, and paydays are fixed, so the 13-week cash flow forecast can name individual items. Thin reserves raise the stakes. A 2016 JPMorgan Chase Institute study of 597,000 small businesses found that “25 percent of small businesses hold fewer than 13 cash buffer days in reserve.”

    Long-range cash depends on decisions not yet made. Hiring plans, pricing, and billing terms drive it, and those live in the income statement and balance sheet. At $8.4M of revenue, one day of days sales outstanding equals $8,400,000 ÷ 365 = $23,014. A slip from 41 to 47 days absorbs 6 × $23,014 = $138,082 of cash.

    Can a startup run both methods at once?

    Yes, and most startups with under 18 months of cash should. The standard structure is a direct forecast for the near term stitched to an indirect model for everything after it.

    • Weeks 1–13: direct, weekly, rebuilt from the bank balance and the aging every week.
    • Months 4–18: indirect, monthly, driven by the operating plan and working-capital days.
    • Each quarter-end: compare the direct total with the indirect bridge for the same quarter.
    • Each close: roll the horizon forward, as a rolling cash flow forecast does.

    The handoff month needs care. Cash that the direct model schedules in week 13 should not reappear in the indirect model’s month 4. One opening balance and one cutoff date prevent the double count.

    How do you choose a cash forecasting methodology?

    Choose by the decision the forecast supports, then by the data the books can actually supply. Four questions settle most cases.

    1. Is there a covenant, payroll, or vendor date that cash must clear in the next six months? If so, run the direct method.
    2. Is the forecast for a board plan, a raise, or an 18-month runway figure? If so, run the indirect method.
    3. Does the business bill annually upfront or carry lumpy annual costs? Then run both, because quarterly averages hide the troughs.
    4. Is the receivables aging reconciled and current? If not, fix the close first; neither method survives bad inputs.

    That last point decides more forecasts than method choice does. Under the Continuous Close Method™, reconciliations run as transactions post, so both models start from verified balances. Kevin Cahill typically sets the horizon split and the seam tolerance with founders before the first build. The step-by-step mechanics sit in our guide on how to build a cash flow forecast, and the monthly re-forecast is part of our outsourced CFO services.

    Sources: FASB Statement No. 95, Statement of Cash Flows (paragraphs 27–29, 106–107); JPMorgan Chase Institute, Cash is King (2016).

    Frequently asked questions

    What is the direct method of cash flow forecasting?

    The direct method projects each major class of cash receipt and payment, such as customer collections, payroll, and vendor bills, on the date it clears the bank. Opening cash plus receipts minus payments gives closing cash for each week or month. That makes it the right tool for horizons of about 13 weeks to 6 months.

    What is the indirect method, and how do you forecast cash flows from financial statements?

    The indirect method starts with projected net income and adds back noncash expenses such as depreciation and stock-based compensation. It then adjusts for projected changes in receivables, payables, prepaid expenses, and deferred revenue. The result is operating cash flow derived from a forecast income statement and balance sheet, suited to 12- to 36-month planning.

    Which method fits short-term vs. long-term forecasting?

    The direct method fits the short term, roughly the next 13 weeks to 6 months, because invoices, bills, and paydays are already known. The indirect method fits the long term because cash beyond two quarters depends on revenue, hiring, and billing-term decisions that live in the projected financial statements.

    Can a startup run both methods at once?

    Yes. A common structure runs a weekly direct forecast for weeks 1 to 13 and a monthly indirect model for months 4 to 18. Both must produce the same operating cash flow for any overlapping quarter, so comparing them at each quarter-end catches missed accruals and unscheduled payments.

    How do you choose a cash forecasting methodology?

    Match the method to the decision. Use the direct method when cash must clear a specific covenant, payroll, or vendor date within six months. Use the indirect method for board plans, fundraising, and runway beyond a year. Businesses with annual billing or lumpy annual costs should run both, starting from reconciled books.

  • Rolling Cash Flow Forecasts: How to Retire the Static Annual Budget

    Rolling Cash Flow Forecasts: How to Retire the Static Annual Budget

    The short answer: A rolling cash flow forecast is a monthly model that always looks the same distance ahead, usually 12 to 18 months, because each close adds a new month as the finished one drops off. In the worked example below, the rolling view shows 9.5 months of runway while the static budget still implies 12.

    • A calendar-year budget sees only 5.5 months ahead on average across the year, and 3 months by the end of September.
    • Re-forecast after every monthly close, using actual cash as the new starting point and drivers for every line.
    • Going-concern rules look one year past the date the statements are issued, so a 12-month budget is often 3.5 months too short.
    • Keep the annual budget as a target, and stop using it to answer cash questions.

    Last updated October 2026.

    The annual budget is approved in December and starts aging in January. By September it describes a quarter that has already happened and a fourth quarter that is three months long. Founders still read it as a forecast.

    The rolling format fixes the horizon problem by design. The sections below define it, compare it with the static budget, set out horizon and cadence by company stage, and run the runway arithmetic for a venture-backed software company whose budget was six months stale.

    Finance lead updating a rolling cash flow forecast on a laptop beside a planner
    Photo by Shixart1985, Wikimedia Commons, CC BY 2.0.

    What is a rolling cash flow forecast?

    A rolling cash flow forecast is a projection of cash receipts and payments that extends a fixed number of months past today and is extended by one month after every close. The horizon never shrinks.

    Each cycle replaces the oldest forecast month with actual results, then adds a new month at the far end. The model is driver-based. Revenue comes from customer counts, pricing, and collection days. Payroll comes from the hiring plan. Vendor spend comes from contracts and run rates.

    Weekly cash timing belongs in a separate tool. The 13-week cash flow forecast names individual invoices and paydays for the next quarter. The rolling model answers a longer question: how many months of cash remain under the current plan.

    How does a rolling forecast differ from a static budget?

    A static budget covers a fixed fiscal year and is revised rarely, so its forward view shrinks every month. A rolling forecast keeps a constant horizon and is rebuilt from actuals after each close.

    DimensionStatic annual budgetRolling cash flow forecast
    HorizonFixed fiscal year; shrinks from 12 months to 0Constant 12 to 18 months
    Update cadenceOnce a year, sometimes one mid-year revisionAfter every monthly close
    Starting pointPrior-year run rateActual cash at the latest close
    BasisDepartment spending targetsDrivers: headcount, customers, collection days
    Forward visibility at end of September3 months12 to 18 months
    Main useTargets, compensation, board approvalRunway, hiring pace, raise timing

    The visibility gap compounds. At the end of month one, a calendar-year budget sees 11 months ahead; at the end of month twelve, it sees none. Averaged across the year, that is (11 + 10 + … + 0) ÷ 12 = 5.5 months of forward view.

    Should you retire the annual budget entirely?

    Retire it as a forecast and keep it as a target. Boards, lenders, and compensation plans still need a fixed yardstick, and the approved budget remains that yardstick.

    The change is in which document answers cash questions. Hiring decisions, raise timing, and runway reporting move to the rolling model. The budget becomes a column in the variance report, where it records what was promised.

    Funded companies that gate spending to milestones can pair the two directly. Our guide to milestone-based budgeting shows how release gates sit on top of a forecast that keeps moving.

    How far forward should a rolling forecast extend?

    Twelve months is the floor for most companies, and 18 months suits venture-backed startups that need to time a raise. The going-concern rules explain the floor.

    Under ASC 205-40, added by FASB Accounting Standards Update 2014-15, management evaluates whether it can meet obligations “within one year after the date that the financial statements are issued (or available to be issued).” The window starts at issuance, not at year-end.

    Run the dates. Fiscal 2026 statements issued on April 15, 2027 require a view through April 15, 2028. That is 15.5 months past the December 31, 2026 balance sheet. A 2027 budget ends on December 31, 2027, which leaves 3.5 months uncovered.

    Public companies face a parallel line. In SEC Release No. 33-10890, the Commission codified guidance that short-term liquidity “covers cash needs up to 12 months into the future.” The 12-month standard is a reporting convention, not an operating ceiling.

    Company profileHorizonRe-forecast cadencePaired tool
    Seed stage, under 18 months of cash12 monthsEvery monthly close13-week forecast
    Series A to B, planning a raise18 monthsMonthly; drivers reviewed quarterly13-week forecast and milestone budget
    Profitable, $10M to $50M revenue12 to 15 monthsMonthly cash, quarterly driversAnnual budget as target

    How often should you re-forecast?

    Re-forecast once a month, within five business days of the close. The close supplies the actuals, and the forecast should never start from unreconciled cash.

    Each cycle follows the same four steps:

    1. Replace last month’s forecast with the closed actuals and post the reconciled bank balance as opening cash.
    2. Log the variance on every line and label it timing, volume, or rate.
    3. Update the drivers that moved: hires, churn, pricing, and days sales outstanding.
    4. Add the new final month and recompute runway.

    Quarterly cycles are too slow for companies with fewer than 18 months of cash. A variance that compounds for 90 days before anyone sees it can consume a full month of runway. The variance analysis at month-end close is the input that keeps each cycle honest.

    What does a rolling re-forecast change? A worked example

    A Series A software company started the year with $7,200,000 in cash. Its approved budget assumed net burn of $400,000 a month, which implied 18 months of runway, through June of the following year.

    Actual net burn averaged $455,000 a month from January through June. Two engineering hires closed early and collections slowed from 38 to 47 days. Six months at $455,000 consumed $2,730,000, leaving $4,470,000 on June 30.

    The budget had expected $4,800,000 ($7,200,000 minus 6 × $400,000). Read against the budget, the company still had 12.0 months of cash ($4,800,000 ÷ $400,000).

    The July re-forecast rebuilt the drivers. Monthly receipts were $143,200, payroll for 38 employees at a $11,400 loaded cost was $433,200, and other operating spend was $180,000. Net burn was $470,000 a month.

    Runway was $4,470,000 ÷ $470,000 = 9.5 months. The board’s policy was to begin a raise with at least 9 months of cash. The budget implied three months of slack; the rolling forecast said the raise had to start in July. The burn rate and runway guide covers the extension levers once the number is known.

    What do your books need to support a rolling forecast?

    A rolling forecast needs a monthly close that finishes on time and reconciles cash, receivables, payables, and deferred revenue. Without that, each cycle restarts from a wrong number.

    • A fixed close calendar: actuals within five business days, so the re-forecast is not a month late.
    • Accrual revenue under ASC 606: deferred revenue and billings separated, so collections can be forecast from contracts.
    • A clean payables subledger: open bills in QuickBooks Online or Bill.com dated to their real due dates.
    • A headcount roster: start dates, salaries, and benefits loads tied to payroll.
    • A stable chart of accounts: forecast lines that map one-to-one to the ledger.

    Under the Continuous Close Method™, reconciliations run as transactions land, so the forecast cycle starts the day the books close. Kevin Cahill typically agrees the horizon, the minimum-cash policy, and the review day with founders before the first model is built. Our outsourced CFO services include the monthly re-forecast. For the underlying mechanics, see how to build a cash flow forecast.

    Frequently asked questions

    What is a rolling cash flow forecast?

    It is a driver-based projection of cash receipts and payments that always covers the same number of months ahead, usually 12 to 18. After each monthly close, the finished month is replaced with actuals and a new month is added at the end, so the horizon never shrinks.

    How does a rolling forecast differ from a static budget?

    A static budget covers one fixed fiscal year and is rarely revised, so its forward view falls from 12 months in January to zero in December. A rolling forecast keeps a constant horizon and restarts from actual cash at every close, which makes it the better tool for runway and hiring decisions.

    How far forward should a rolling forecast extend?

    Twelve months is the practical minimum, and venture-backed startups planning a raise often use 18. Going-concern guidance in ASC 205-40 looks one year past the date the financial statements are issued, so a forecast that ends at the fiscal year-end usually falls short of that window.

    How often should you re-forecast?

    Monthly, within about five business days of the close, is the standard cadence for companies with less than 18 months of cash. Each cycle posts actuals, labels variances, updates the drivers that moved, and adds a new final month before runway is recalculated.

    What do your books need to support a rolling forecast?

    The books need an on-time monthly close with reconciled cash, receivables, payables, and deferred revenue, plus a headcount roster tied to payroll. Without reconciled actuals, each re-forecast starts from a wrong opening balance and the runway figure drifts.